Cash Flow Forecast Variance Analysis Controls for UAE Businesses
Editorial responsibility: Valusage Business Advisors Editorial Practice (Editorial Practice)
Direct answer
Cash-flow forecast variance analysis should compare each forecast receipt and payment with reconciled bank actuals, separate timing differences from value changes and omitted items, assign the underlying cause to a named owner, and feed approved changes into the next forecast. Accuracy should be assessed by horizon and cash category, not only by whether the closing bank balance happened to be close.
Management decision map
From information to a controlled decision
- 01Measure
- 02Forecast
- 03Decide
- 04Act
Illustrative evidence trend
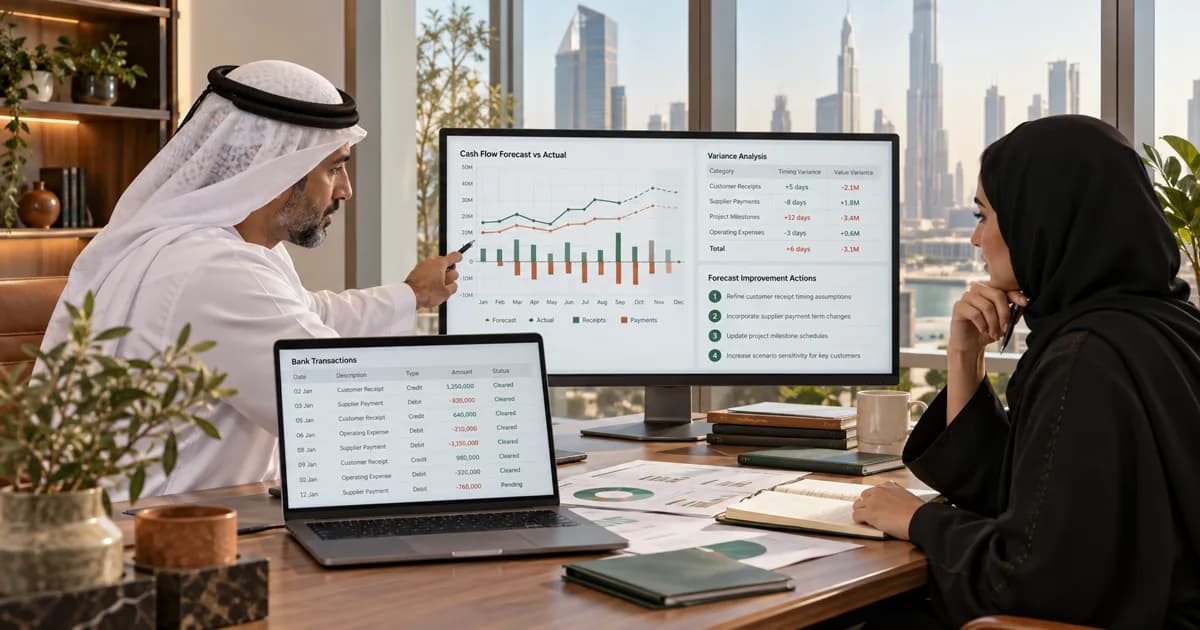
Decision supportA cash forecast improves only when the business learns systematically from what happened. Comparing the final bank balance alone can hide large offsetting errors: receipts may arrive late while payments are also delayed, producing a plausible closing number for the wrong reasons.
Freeze the forecast version
Store the approved forecast at the start of each review period with its preparation date, horizon, entities, currencies and assumptions. Do not overwrite it after actual results are known. Later scenario changes should remain separate so management can distinguish genuine forecast accuracy from a revised view.
Reconcile actual cash first
Use bank transactions reconciled to the ledger or a controlled treasury record. Exclude internal transfers from group-level inflow and outflow analysis where appropriate, while preserving entity-level visibility. Identify uncleared transactions, duplicate imports and value-date differences before calling them forecast errors.
Match by cash category and expected date
Connect customer receipts, supplier payments, payroll, tax payments, debt service, capital expenditure and other material flows to their forecast lines. Where one actual amount settles several forecast items, preserve a documented allocation. Unmatched actuals should be classified rather than placed in a permanent “other” category.
Separate four variance types
A timing variance occurs when the amount is broadly right but the date changes. A value variance reflects a changed amount. A missing-item variance means the forecast omitted a real flow. A classification variance means the total may be right but the category or entity was wrong. Keeping those causes separate gives management a clearer improvement action.
Analyse by forecast horizon
Near-term weeks should normally use more specific evidence than later periods. Compare accuracy for week one, weeks two to four and the remaining horizon rather than combining everything. A collections assumption may be dependable for seven days but weak for eight weeks; the review should reveal that boundary.
Record root causes and actions
Link material differences to customer promise dates, supplier-term changes, payroll updates, project milestones, purchasing decisions or missing source data. Assign the action to the operating owner who can improve the input, not only to finance. Repeat causes should lead to a changed data source, cut-off or assumption method.
Report accuracy without false precision
Show AED variance, timing days, category and horizon. Percentage measures can mislead when the expected amount is small or zero, so pair them with absolute value. Distinguish controllable forecasting errors from approved business decisions made after the forecast was frozen.
Cash forecast variance checklist
1. Freeze and timestamp the approved forecast. 2. Reconcile actual cash to bank and ledger evidence. 3. Match receipts and payments by category and date. 4. Separate timing, value, missing and classification variances. 5. Measure accuracy by forecast horizon. 6. Assign root causes to operating owners. 7. Update assumptions through controlled changes. 8. Track whether repeat variances reduce over time.
IAS 1 includes a statement of cash flows within a complete set of financial statements, while the Conceptual Framework addresses useful financial information. A rolling management forecast is different from that statutory statement; this guide supports internal liquidity decisions and does not guarantee cash availability or business outcomes.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 CFO, Finance and Cash FlowCustomer Credit Limit and Order Release Controls for UAE Businesses →
 Accounting and BookkeepingPurchase Order Commitment and Budget Control for UAE Businesses →
 Accounting and BookkeepingSales Commission Calculation and Payout Reconciliation Controls in the UAE →
 CFO, Finance and Cash FlowCost Centre Master Data and Expense Allocation Controls for UAE Groups →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What is a cash-flow forecast timing variance?+
It occurs when the expected cash amount is broadly correct but the receipt or payment happens in a different period from the frozen forecast.
Why analyse forecast accuracy by horizon?+
Near-term forecasts use more specific evidence than later periods, so separate horizons show where assumptions become less reliable.
Should internal bank transfers count as cash-flow variances?+
Preserve them for entity-level control, but avoid treating them as external group inflows or outflows when reviewing consolidated liquidity.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Turn forecast differences into better liquidity decisions
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Turn forecast differences into better liquidity decisions
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.