Purchase Order Commitment and Budget Control for UAE Businesses
Editorial responsibility: Valusage Business Advisors Editorial Practice (Editorial Practice)
Direct answer
Purchase-order commitment control should reserve approved spend against the relevant entity, department, project and period before an invoice arrives. Finance should reconcile open purchase orders to receipts and invoices, remove cancelled or completed commitments, investigate stale balances and require documented approval where a request would exceed the available budget or bypass the normal purchasing route.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
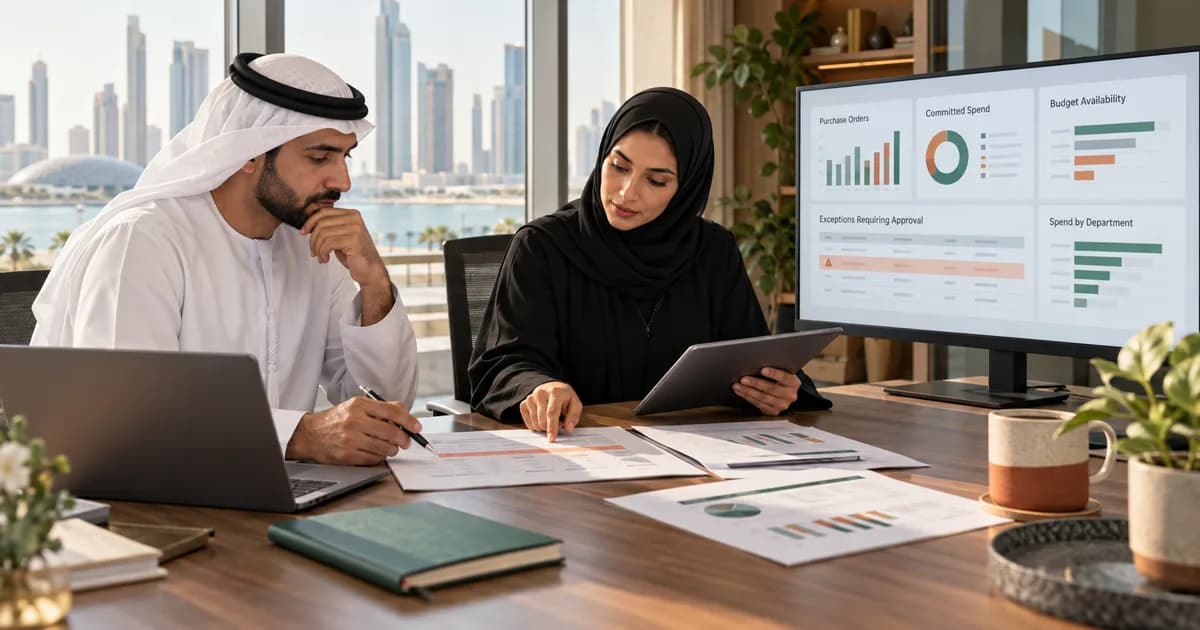
Decision supportA budget can appear available even when managers have already approved purchase orders that suppliers have not yet invoiced. Commitment reporting closes that timing gap by showing approved future spend alongside actual costs and remaining budget.
Define when a commitment begins
Use an approved purchase order or another specifically authorised instrument as the normal commitment point. A requisition may indicate demand but should not consume budget unless policy says it is sufficiently approved. Record entity, supplier, department, project, account, currency, order date, delivery period, requester, approver and buyer.
Validate budget before approval
Compare the requested amount with the approved budget, actual cost already recorded and existing commitments. Use the same account, department and project structure as management reporting. If coding differs between procurement and finance, the availability calculation will be misleading even when each system balances independently.
Reserve the approved amount once
When the purchase order is approved, reserve its remaining value. Amendments should update the commitment through version-controlled approval rather than create a second reservation. Multi-currency orders need a documented rate approach for management reporting, with currency movement kept distinguishable from additional purchasing.
Reduce commitments through evidence
Use goods or service receipt evidence and supplier invoices to reduce open commitments according to policy. Partial receipts should leave the genuine undelivered balance open. The commitment should not disappear merely because an invoice was entered if the order still has undelivered lines, nor remain fully open after the obligation has been completed.
Review stale and unusual purchase orders
Age open orders by expected delivery or completion date. Investigate dormant orders, duplicate lines, closed projects, suppliers no longer in use, orders with invoices but no receipt, and receipts without invoices. Ask the owner to confirm whether the balance is still expected, should be cancelled or requires a supported close adjustment.
Govern over-budget and retrospective buying
An over-budget request should identify the amount, business reason, funding source, decision owner and any revised forecast. Do not make “urgent” a standing approval category. Retrospective purchase orders should appear in an exception report because they approve spend after the supplier commitment has already arisen.
Reconcile the commitment report
At each reporting date, reconcile open purchase orders to the procurement system, receipts, accounts payable and the management budget. Explain differences between committed, accrued and invoiced values. Commitment reporting is a management control; it should not be confused with an accounting liability without applying the entity’s recognition policy to the facts.
Purchase-order commitment checklist
1. Define the authorised commitment point. 2. Match procurement coding to the reporting hierarchy. 3. Test available budget before purchase-order approval. 4. Reserve each approved amount only once. 5. Reduce commitments using receipt and invoice evidence. 6. Age stale, partial and dormant purchase orders. 7. Approve over-budget and retrospective exceptions explicitly. 8. Reconcile commitments, actuals and close adjustments.
The UAE Commercial Companies Law establishes accounting-record expectations, and the IFRS Conceptual Framework describes concepts supporting useful financial information. This article addresses management commitment control rather than procurement law, contractual enforceability or accounting recognition for a specific purchase.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 CFO, Finance and Cash FlowCash Flow Forecast Variance Analysis Controls for UAE Businesses →
 CFO, Finance and Cash FlowCustomer Credit Limit and Order Release Controls for UAE Businesses →
 Accounting and BookkeepingSales Commission Calculation and Payout Reconciliation Controls in the UAE →
 CFO, Finance and Cash FlowCost Centre Master Data and Expense Allocation Controls for UAE Groups →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What is a purchase-order commitment?+
It is approved future spend reserved for management reporting before the related supplier invoice is fully recorded as an actual cost.
Should a requisition reduce the available budget?+
Only if the documented policy treats that approval stage as a commitment. Otherwise, reserve the amount when the purchase order or equivalent authority is approved.
How should stale purchase orders be handled?+
Confirm the expected delivery with the owner, investigate receipts and invoices, then retain, amend or cancel the remaining commitment through an approved record.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
See committed spend before the invoice reaches the ledger
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
See committed spend before the invoice reaches the ledger
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.