Sales Commission Calculation and Payout Reconciliation Controls in the UAE
Editorial responsibility: Valusage Business Advisors Editorial Practice (Editorial Practice)
Direct answer
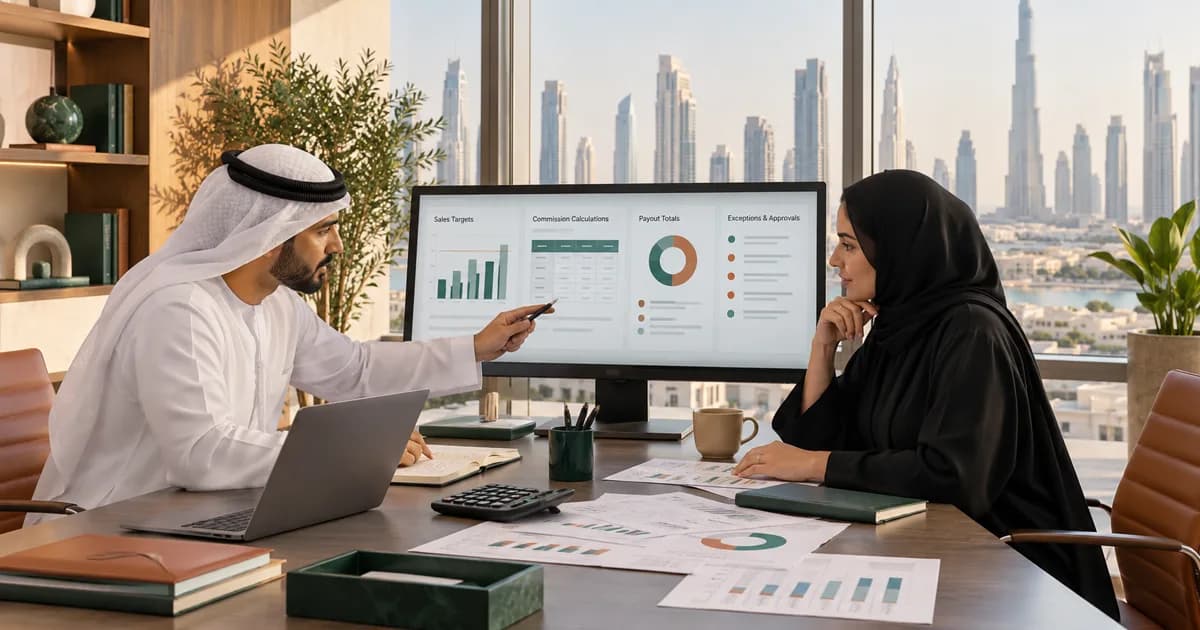
A controlled sales-commission process should use one approved and versioned scheme, define the eligible sales population and trigger, reconcile source transactions to the calculation, review cancellations and credits, approve exceptions independently, and match the final employee or agent-level payout file to payroll or accounts payable and the ledger. Finance should never calculate from an editable sales summary that cannot be traced to source transactions.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportCommission errors often start before the calculation. If the scheme version, eligible sale, collection trigger, territory or responsible person is unclear, an accurate spreadsheet formula can still produce the wrong payout. The control should connect approved commercial rules to source transactions and the final recorded payment.
Lock the approved scheme version
Store the approved rules, effective period, covered roles, calculation basis, trigger, rates, tiers, caps, exclusions and approval authority. Keep later amendments as a new version with an effective date. Do not apply a changed rate retrospectively unless the authorised decision and contractual basis are documented.
Define the eligible sales population
State whether eligibility follows booking, delivery, invoice, collection or another approved event. Extract the population from a controlled system and reconcile totals to the relevant sales, billing or cash record. Identify the legal entity, customer, salesperson or agent, transaction, currency and period. Manual additions need the same evidence as system-generated lines.
Control ownership and attribution
Use approved master data for territory, account ownership and team splits. Record transfers, joint sales and manager overrides before calculation cut-off. A salesperson should not be able to change transaction ownership after seeing the payout result without independent approval and a retained reason.
Review cancellations, returns and credits
Apply the approved treatment consistently to cancellations, credit notes, refunds, bad debts and later collections. Keep the original earning and any reversal traceable rather than deleting prior calculation lines. Where treatment is disputed, place the item in an exception register instead of making an undocumented adjustment.
Recalculate and review exceptions
Protect formulas, reconcile rate tables to the approved scheme and test tier boundaries. Compare current payouts with sales, prior period, targets and expected trends. Investigate round-sum overrides, duplicate transaction IDs, negative results, unusually high changes and employees or agents with no source sales.
Match the payout to accounting records
Reconcile the approved person-level schedule to the payroll or accounts-payable upload, payment evidence and ledger posting. Separate gross calculation, authorised adjustments, recoveries and final payout. Preserve evidence of reviewer approval and rejected items. No one should amend the payment file after approval without a new control record.
Close the cycle and improve data
Provide each participant with an appropriate statement or query route based on company policy. Track calculation errors by root cause: scheme ambiguity, master-data ownership, delayed credits, source-system gaps or manual override. Update the process rather than accepting repeated correction work as normal.
Commission reconciliation checklist
1. Lock the approved scheme and effective version. 2. Define the eligible transaction and trigger. 3. Reconcile source sales to the calculation population. 4. Control attribution, splits and manual additions. 5. Apply cancellations, credits and reversals consistently. 6. Test formulas, tiers, duplicates and exceptions. 7. Match approved payouts to payment and ledger records. 8. Retain approvals, queries and root-cause actions.
IAS 8 addresses accounting policies and correction of errors, while IAS 1 sets overall presentation requirements. This guide describes calculation and reconciliation controls. It does not determine contractual entitlement, employment rights, tax treatment or whether a specific commission should be recognised in a particular period.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 CFO, Finance and Cash FlowCash Flow Forecast Variance Analysis Controls for UAE Businesses →
 CFO, Finance and Cash FlowCustomer Credit Limit and Order Release Controls for UAE Businesses →
 Accounting and BookkeepingPurchase Order Commitment and Budget Control for UAE Businesses →
 CFO, Finance and Cash FlowCost Centre Master Data and Expense Allocation Controls for UAE Groups →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
Which sales should be included in a commission calculation?+
Use the event defined in the approved scheme, such as booking, delivery, invoicing or collection, and reconcile the population to controlled source records.
How should credit notes affect commission?+
Apply the approved scheme consistently and retain the original earning plus any later reversal or adjustment as separate traceable records.
What should finance reconcile before commission payout?+
Reconcile eligible transactions, ownership, rates, tiers, exceptions and the approved person-level schedule to the payment file and ledger posting.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Make every commission payout traceable to approved rules and source sales
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Make every commission payout traceable to approved rules and source sales
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.