Customer Credit Limit and Order Release Controls for UAE Businesses
Editorial responsibility: Valusage Business Advisors Editorial Practice (Editorial Practice)
Direct answer
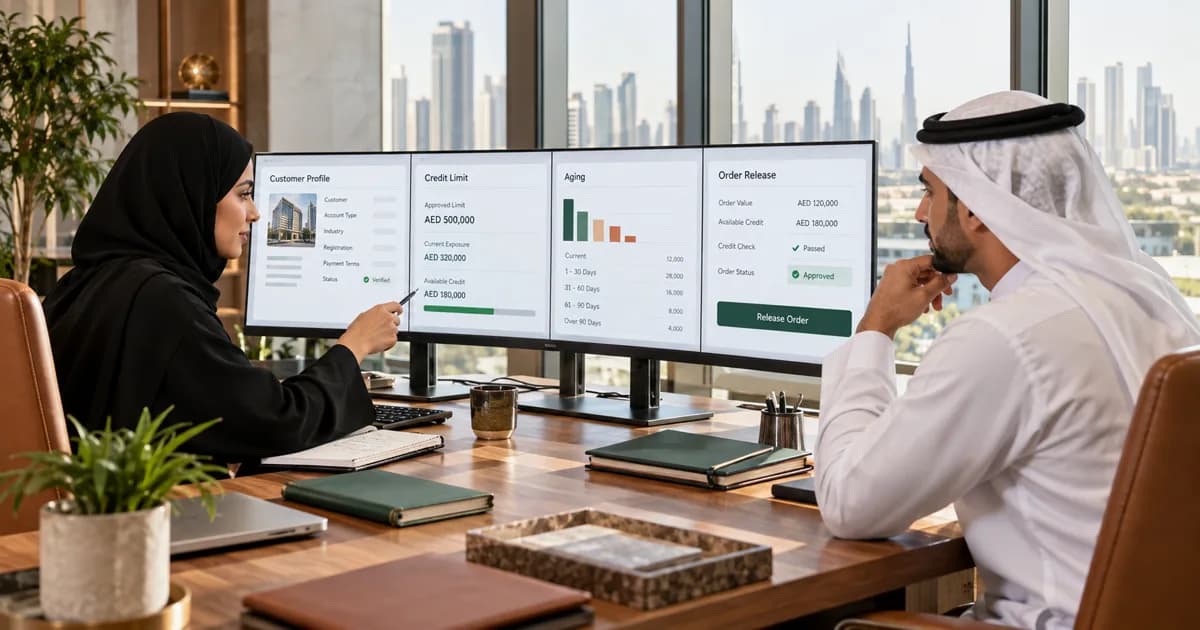
A controlled customer credit process should verify the legal customer record, assign an approved limit and payment terms, calculate current exposure from open invoices and unbilled or pending orders, identify overdue balances and require documented approval before releasing an order that exceeds defined conditions. Sales should not be able to create the customer, change the limit and approve its own exception.
Management decision map
From information to a controlled decision
- 01Measure
- 02Forecast
- 03Decide
- 04Act
Illustrative evidence trend
Decision supportRevenue growth can consume cash when orders are released without a clear view of the customer, existing exposure or overdue balances. A practical credit control connects the customer master record, commercial terms, accounts receivable and the next order decision before additional value leaves the business.
Verify the customer record first
Record the correct legal name, entity, billing address, contact route, currency, agreed payment terms and responsible commercial owner. Validate changes through an approved request and retain the source. Duplicate accounts can divide exposure and make an over-limit customer appear available for more credit, so search existing records before creating another customer.
Set an approved limit and review date
The limit should be an explicit management decision supported by the information the business considers relevant, such as trading history, expected order pattern, payment behaviour, external evidence where lawfully obtained and the commercial importance of the relationship. Record the approver, effective date, review date and any conditions. Do not leave a temporary limit in place indefinitely.
Calculate total exposure consistently
Define what consumes the limit. A useful exposure view normally includes unpaid invoices, overdue balances, delivered but unbilled items and approved or pending orders that would create additional exposure. Reconcile the calculation to the receivables ledger and order system. A credit-limit report that ignores new orders until invoicing happens reacts too late.
Use ageing as a decision input
Separate current, overdue and disputed balances. A customer can remain within its numerical limit while repeatedly paying late. Document whether overdue or disputed items block release, require a partial payment or need a named exception. Avoid hiding genuine disputes inside general overdue totals; record the issue, owner and expected resolution.
Control the order-release decision
Configure normal orders to pass when the customer is active, exposure remains within the approved limit and no blocking condition exists. Route exceptions to an authorised approver independent of the salesperson requesting release. The record should show the order, exposure before and after release, exception reason, approver, conditions and expiry.
Separate duties and urgent overrides
Where team size permits, separate customer creation, credit approval, order entry, release and cash allocation. In a smaller business, use compensating review of master-data changes and override reports. An urgent release should still leave a complete record; urgency changes timing, not evidence.
Review outcomes and recurring exceptions
Monitor overdue value, limit utilisation, blocked orders, overrides, promised payment dates, disputes and bad-debt indicators selected by management. Review customers that regularly require exceptions and compare actual payment behaviour with the basis used when the limit was approved. Close or reduce unused limits where the relationship has changed.
Customer credit control checklist
1. Verify the legal customer and prevent duplicate accounts. 2. Record approved terms, limit, approver and review date. 3. Define invoices, unbilled items and orders included in exposure. 4. Reconcile exposure to receivables and order records. 5. Apply documented ageing and blocking conditions. 6. Route overrides to an independent authorised approver. 7. Retain every exception, condition and expiry date. 8. Review payment behaviour and recurring overrides.
The IFRS Conceptual Framework addresses useful financial information, while IAS 1 includes presentation of financial position and cash flows. This operational control supports reliable receivables and cash information; it does not determine a customer’s legal liability, impairment measurement or enforceability of commercial terms.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 CFO, Finance and Cash FlowCash Flow Forecast Variance Analysis Controls for UAE Businesses →
 Accounting and BookkeepingPurchase Order Commitment and Budget Control for UAE Businesses →
 Accounting and BookkeepingSales Commission Calculation and Payout Reconciliation Controls in the UAE →
 CFO, Finance and Cash FlowCost Centre Master Data and Expense Allocation Controls for UAE Groups →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What should consume a customer credit limit?+
Use one documented definition that normally considers unpaid invoices, overdue balances, delivered but unbilled items and orders that would create additional exposure.
Can sales approve an over-limit order?+
The business should route exceptions to an authorised approver independent of the salesperson requesting release and retain the reason, conditions and expiry.
How often should customer credit limits be reviewed?+
Set a documented review date and reassess earlier when payment behaviour, order volume, disputes or available evidence changes materially.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Connect commercial growth to controlled credit exposure
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Connect commercial growth to controlled credit exposure
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.