
Supplier Return, Debit Note and Credit Reconciliation Controls in the UAE
Editorial responsibility: Valusage Business Advisors Editorial Practice (Editorial Practice)
Direct answer
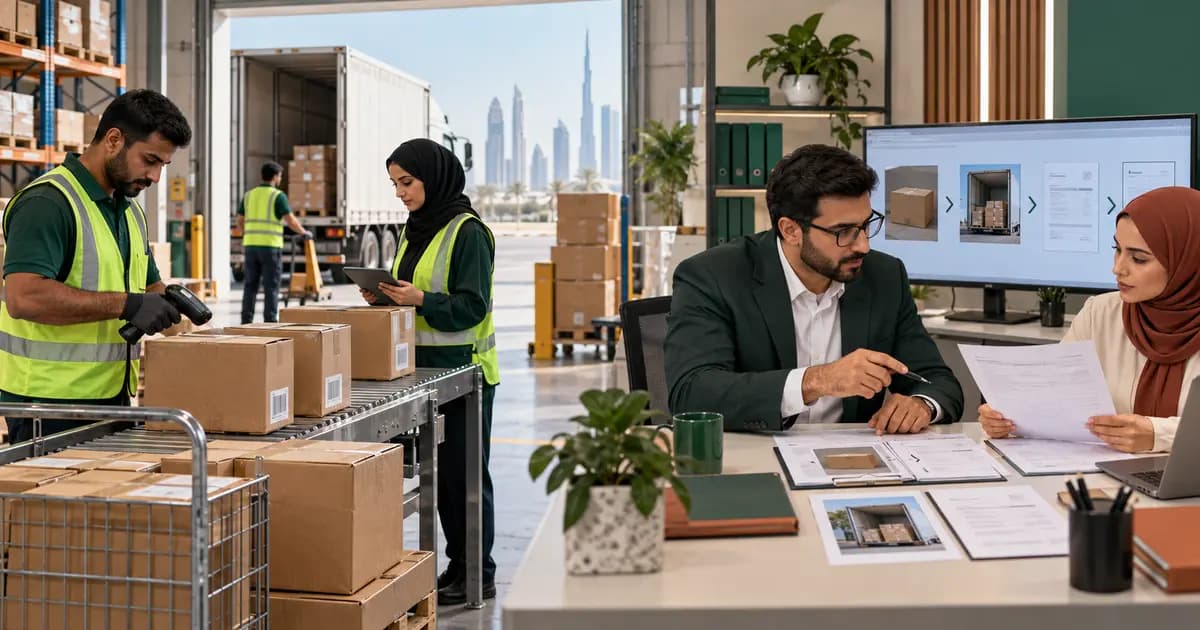
A supplier-return reconciliation should connect the authorised return request, item and quantity, warehouse dispatch evidence, original purchase and receipt, debit note, supplier acknowledgement, credit note or replacement, inventory movement and accounts-payable allocation. Finance should age unmatched returns, prevent duplicate deductions and confirm that credits are applied to the correct legal entity, supplier account and invoice before close.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportA physical return can leave the warehouse today while the supplier credit arrives weeks later. Without one control record, inventory may reduce while the payable remains unchanged, a debit note may be duplicated, or a credit may sit unallocated on the supplier account.
Authorise the return reason
Record the supplier, legal entity, item, quantity, unit, original purchase order and receipt, reason, condition, value and approver. Separate quality issues, over-delivery, incorrect specification, commercial agreement and transport damage where responsibilities differ.
Link warehouse dispatch to finance
Retain the return authorisation, dispatch note, carrier evidence and supplier receipt or acknowledgement. The warehouse movement and finance record should use the same return reference. Investigate stock movements with no authorised supplier return.
Prepare the debit note from source data
Calculate the claimed value using the approved price, quantity and agreed deductions. Reference the original supplier invoice and purchase record. Restrict manual changes to the supplier, value and currency after approval. A debit note documents the claim; it does not prove that the supplier accepted it.
Match the supplier outcome
Record whether the supplier issues a credit note, replacement goods, repair, refund or rejection. Match the outcome to the original return and compare value, tax, quantity and currency. Route differences to procurement and finance with a named owner.
Reconcile inventory and payables
Confirm the physical and system inventory movements, debit-note or return account, supplier credit, bank receipt where relevant and accounts-payable allocation. Prevent the same return from reducing both an invoice payment and a separately posted supplier credit.
Age open returns
Age from dispatch and show expected supplier response dates. Review goods returned without supplier acknowledgement, credits received but not allocated, replacements not received and value differences. Escalate repeated supplier or location exceptions.
Supplier return checklist
1. Approve item, quantity, reason and value. 2. Link the return to the original purchase and receipt. 3. Retain dispatch and supplier acknowledgement. 4. Issue a controlled debit note where applicable. 5. Match credit, replacement, repair or refund. 6. Reconcile inventory and accounts payable. 7. Prevent duplicate deductions and credits. 8. Age and escalate every unresolved return.
IAS 2 addresses inventory measurement. The accounting and tax treatment of a specific return or credit depends on the facts and supporting documents. This guide focuses on operational evidence and reconciliation.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Accounting and BookkeepingCustomer Deposit and Unapplied Cash Reconciliation Controls in the UAE →
 Industry GuidanceUtility Account, Deposit and Meter Reconciliation Controls for UAE Multi-Site Businesses →
 Industry GuidanceVendor Rebate Accrual and Claim Reconciliation Controls for UAE Distributors →
 Accounting and BookkeepingAccrual Ageing and Reversal Controls for UAE Month End Close →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What evidence should support a supplier return?+
Retain the approval, original purchase and receipt, item and quantity, dispatch evidence, supplier acknowledgement, debit note and final supplier outcome.
Is a debit note the same as a supplier credit note?+
No. A debit note records the buyer’s claim. The supplier credit note or other agreed outcome confirms how the supplier settled that claim.
How should old supplier returns be managed?+
Age them from dispatch, assign an owner and track missing acknowledgement, disputed value, replacement, credit or refund until inventory and payables agree.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Connect every returned item to the final supplier credit or resolution
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Connect every returned item to the final supplier credit or resolution
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.