
Maintenance Work Order, Service Receipt, Accrual and Invoice Controls in the UAE
By Valusage Technical Practice
Editorial responsibility: Valusage Business Advisors Editorial Practice
Direct answer
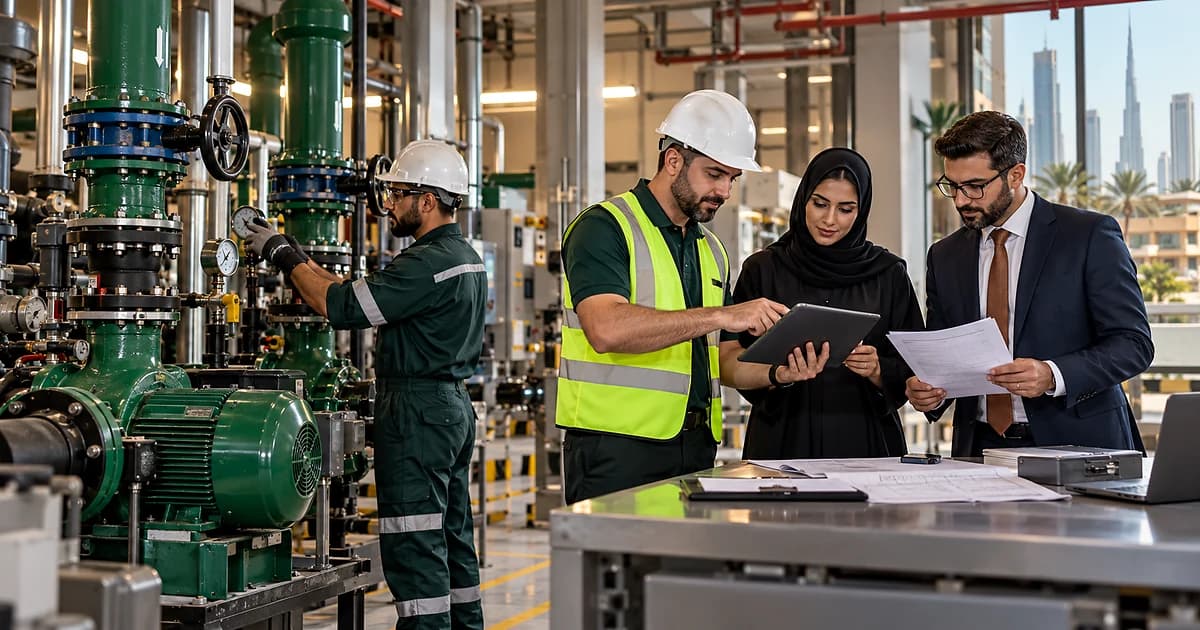
A UAE multi-site business should give every maintenance job an approved work order containing the site, asset, scope, supplier, commercial basis, budget owner and approval limit. Operations should confirm the service actually completed, including date, quantity, parts and exceptions; finance should reconcile that receipt to the month-end accrual, supplier invoice and payment. An open purchase order is not proof of completion, and an invoice should not be approved solely because the supplier refers to a valid work-order number.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportMaintenance spending passes through facilities teams, site managers, procurement, finance and suppliers. The control breaks when each party holds only part of the record. One work-order reference should connect authorisation, completion, accrual, invoice and payment.
Authorise the work before it starts
Record the legal entity, site, asset or location, issue, requested scope, urgency, supplier, quotation or rate card, budget code, estimated value and approvers. Emergency work should use a documented retrospective approval path with a short deadline, not a permanent exemption from purchasing control.
Confirm the service receipt
The person receiving the work should record completion date, labour or visit quantity, materials or parts, asset status, incomplete items and follow-up work. Attach service reports, photographs or readings proportionate to the job. A supplier timesheet or engineer report supports the receipt but should be confirmed by an accountable site representative.
Build the month-end accrual from evidence
At cut-off, list work orders that are completed or partly completed but not invoiced. Accrue from confirmed service receipt and the best supported amount, not from every open order. Show work-order value, completion status, accrual basis, prior accrual, invoice received and reversal or true-up. Review old accruals so estimates do not roll forward without challenge.
Match the invoice to the job
Compare supplier, site, work-order reference, scope, completion evidence, rate, parts, call-out fees, taxes and prior invoices. Check for split billing, duplicate invoices and invoices against cancelled or uncompleted work. Route price or scope differences back to an authorised owner rather than editing the receipt evidence.
Reconcile to payment and asset history
After approval, link the invoice and payment to the same work order. Reconcile the maintenance subledger, accrual schedule, payables and bank settlement. Retain asset history for recurring failures, warranties and supplier performance. Separately assess whether unusual expenditure needs accounting review rather than automatically treating every maintenance invoice the same way.
Maintenance control checklist
1. Approve scope, supplier, rate and budget owner. 2. Use a unique work-order reference for every job. 3. Confirm service receipt and incomplete work. 4. Accrue completed work from supported evidence. 5. Match invoice scope, price, parts and prior billing. 6. Clear or true-up the accrual once invoiced. 7. Link approved invoices to payment records. 8. Review repeat repairs, ageing and exceptions by site.
IAS 7 addresses cash-flow information and the Conceptual Framework supports faithful, relevant reporting. The timing and classification of expenditure depend on the nature of the work and applicable accounting policy. This is an operational finance-control framework.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Accounting and BookkeepingConsignment Inventory Ownership, Count and Settlement Controls in the UAE →
 Industry GuidancePromotional Discount, Coupon and Co-Funding Reconciliation Controls in the UAE →
 Industry GuidanceReturnable Packaging, Crate and Pallet Deposit Reconciliation Controls in the UAE →
 CFO, Finance and Cash FlowCorporate Insurance Policy, Premium and Claim Reconciliation Controls in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
Does an open maintenance purchase order prove that an accrual is required?+
No. The accrual basis should reflect supported work completed or received by period end, considering the facts and accounting policy, not merely an open order.
What should a maintenance service receipt contain?+
Include the site, asset, work order, completion date, labour or visit quantity, parts, work performed, incomplete items, receiver confirmation and supporting evidence.
How can finance prevent duplicate maintenance invoices?+
Match supplier invoice number, work order, service date, site, amount and prior billing, and block or investigate duplicates before approval and payment.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Connect maintenance approval and completion to accrual, invoice and cash
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Connect maintenance approval and completion to accrual, invoice and cash
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.