
Consignment Inventory Ownership, Count and Settlement Controls in the UAE
By Valusage Technical Practice
Editorial responsibility: Valusage Business Advisors Editorial Practice
Direct answer
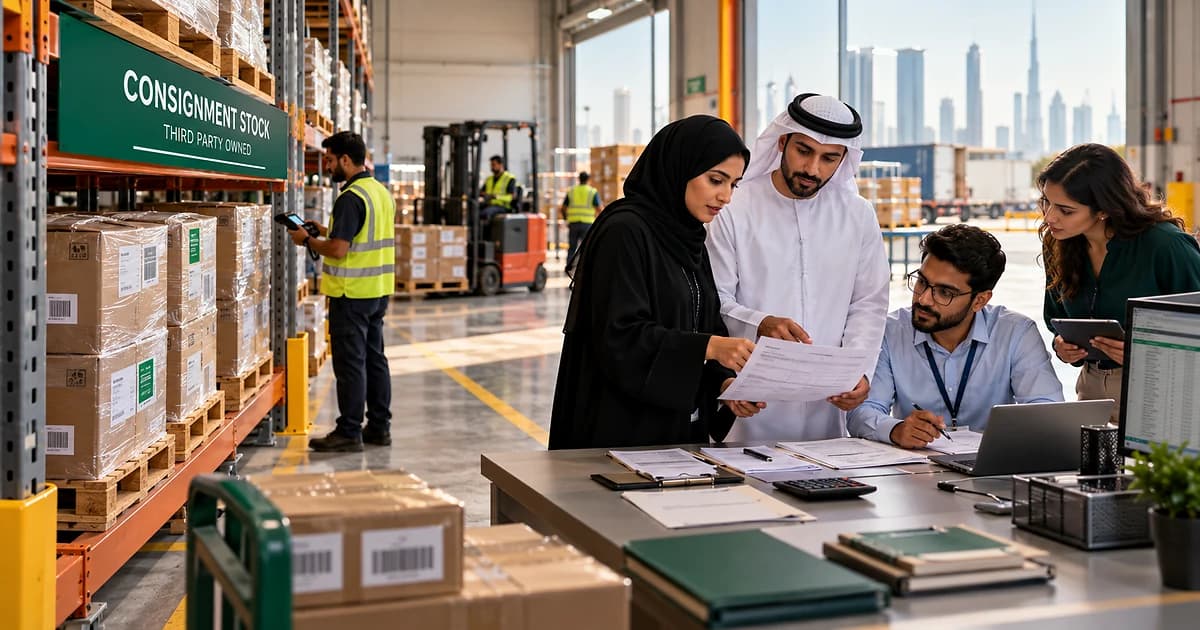
A UAE business should control consignment inventory with a signed agreement and a dedicated register that identifies the legal owner, custodian, location, item, quantity, unit basis, receipt, sale, return, damage and settlement status. The custodian should count consigned stock separately from owned stock; finance should reconcile movements and sales to the owner statement; and both parties should resolve differences before settlement. Physical possession alone does not establish ownership, and a supplier invoice should not replace the contract assessment.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportConsignment arrangements create a recurring control problem: goods may be on one party's premises while ownership, sales risk and settlement obligations remain with another. A standard stock report rarely explains that distinction. The control must connect the contract, custody record, count, sale or return event and settlement.
Define ownership and custody before receipt
Record the consignor, consignee, relevant legal entities, contract reference, effective dates, title-transfer terms, selling authority, price basis, commission or margin, loss responsibility, insurance responsibility and return rights. Finance should retain the reviewed conclusion for how the arrangement is reflected in each party's records. Do not infer ownership from warehouse location, barcode ownership or the timing of a supplier invoice.
Create a separate consignment register
Give each receipt a consignment reference linked to item code, batch or serial number where relevant, quantity, unit of measure, location, receipt date and condition. Tag consigned goods physically and in the inventory system. Keep owner and custodian fields visible so stock cannot be silently included in ordinary purchases, unrestricted transfers or owned-inventory valuation.
Control every movement
Record sales, returns, transfers, damage, expiry, adjustments and goods returned to the owner using the same reference. Restrict manual quantity changes and preserve the user, timestamp, reason and approval. Where the custodian can sell the goods, reconcile point-of-sale or dispatch evidence to the movement register rather than relying only on a periodic owner statement.
Count stock with both records in view
Count consigned stock separately during cycle and period-end counts. Compare the physical result with the custodian's subledger and the owner's statement. Investigate timing differences, unit-of-measure errors, unrecorded sales, damaged goods and stock at another site. Record the agreed disposition of each variance instead of forcing the count to the system balance.
Reconcile settlement and close-out
Prepare a roll-forward from opening units through receipts, sales, returns, losses and closing units. Match sales or usage to the agreed price, commission, fees, credits and settlement paid or received. Confirm aged unsold stock, contract expiry, final returns and unresolved balances. A complete close-out ends both the custody record and the related receivable, payable or clearing balance.
Consignment inventory checklist
1. Approve a contract that states ownership and transfer terms. 2. Tag all consigned stock by owner, site and reference. 3. Separate consignment records from owned inventory. 4. Capture every receipt, sale, return, transfer and loss. 5. Count stock against custodian and owner records. 6. Reconcile sales, commissions, credits and cash. 7. Age unexplained count and settlement differences. 8. Close expired arrangements with final confirmations.
IAS 2 addresses inventory measurement and expense recognition, while IFRS 15 provides the revenue-recognition framework. The accounting outcome for a consignment arrangement depends on the contract and facts. This article is a custody and reconciliation framework, not a contract-specific accounting conclusion.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Accounting and BookkeepingMaintenance Work Order, Service Receipt, Accrual and Invoice Controls in the UAE →
 Industry GuidancePromotional Discount, Coupon and Co-Funding Reconciliation Controls in the UAE →
 Industry GuidanceReturnable Packaging, Crate and Pallet Deposit Reconciliation Controls in the UAE →
 CFO, Finance and Cash FlowCorporate Insurance Policy, Premium and Claim Reconciliation Controls in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
Should consignment inventory be counted with ordinary owned stock?+
It should be physically counted, but identified and reconciled separately by owner and contract so custody is not confused with ownership.
What should a consignment inventory register contain?+
Include owner, custodian, contract, item, location, quantity, receipt, sale, return, damage, count variance, settlement and supporting references.
How often should consignment settlements be reconciled?+
Use the contract cycle and month-end close, with more frequent reconciliation for high-volume or high-value goods and immediate review of material differences.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Separate consignment ownership, custody, counts and settlement
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Separate consignment ownership, custody, counts and settlement
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.