Supplier Statement Reconciliation and Missing Invoice Controls in the UAE
Editorial responsibility: Valusage Business Advisors Editorial Practice (Editorial Practice)
Direct answer
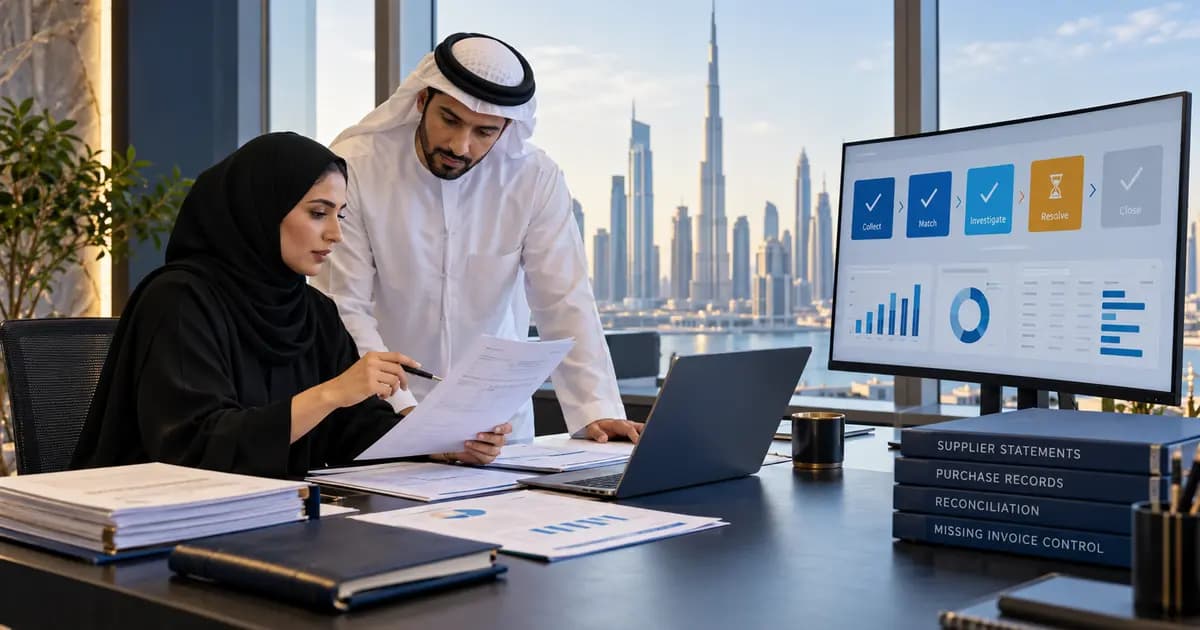
A supplier statement reconciliation should compare every supplier invoice, credit, payment and open item on the supplier statement with the accounts-payable ledger, purchase and receipt evidence. Missing documents, unallocated payments, duplicated charges and disputes should be assigned to named owners, aged and resolved before close, while supplier master-data changes remain independently controlled.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportAn accounts-payable ledger can balance internally and still omit invoices or credits that appear on a supplier's records. Regular supplier statement reconciliation helps UAE businesses find those gaps before they distort expenses, cash forecasts, supplier relationships and period-end liabilities.
Prioritise the supplier population
Create a reconciliation timetable using spend, transaction volume, payment criticality, ageing, dispute history and balance volatility. Reconcile strategic and high-risk suppliers monthly, while using a documented cadence for lower-risk vendors. Include zero-balance suppliers where recent activity or unapplied payments make an omission possible.
Obtain the statement independently
Request statements through an approved supplier contact or portal rather than relying only on documents forwarded with a payment request. Confirm the legal entity, supplier account number, statement date, currency and branch. A statement addressed to another group entity should not be forced into the wrong ledger.
Match the four transaction types
Compare invoices, credit notes, payments and adjustments line by line or through a controlled automated match. Use invoice number, date, gross amount, currency and purchase reference. Then investigate entries that exist on only one side. A supplier invoice absent from the ledger may reflect a missing document, goods-receipt timing, a dispute or an invoice sent to the wrong entity.
Investigate missing invoices without bypassing controls
Obtain a valid invoice and connect it to the purchase order, goods or service evidence and approval. Do not post from the statement alone when the normal evidence is still required. If the service or goods were received before the invoice, finance should assess whether a supported accrual or goods-received-not-invoiced entry is needed under the applicable close policy.
Clear unallocated payments and credits
Payments may remain unmatched because remittance information was incomplete, the supplier allocated cash to a different invoice or a group entity paid centrally. Credit notes may sit outside the ledger or be applied against the wrong invoice. Record the resolution, cross-entity approval where relevant and any supplier confirmation instead of netting unexplained amounts.
Detect duplicates and master-data risk
Search for the same invoice number with spacing or punctuation differences, repeated amounts, split postings and invoices paid from more than one entity. Keep supplier-bank-detail verification outside the reconciliation preparer's control. Statement reconciliation is useful detective control, but it should not authorise a bank-detail change or payment on its own.
Close the exception register
For every difference, record the type, amount, ageing, owner, due date, evidence required and outcome. Separate timing differences from true errors. Review recurring root causes such as invoices sent to individuals, late receipt confirmations, poor remittance advice or duplicate supplier accounts. Management should see material unresolved differences before the close is approved.
Supplier statement checklist
1. Define the supplier population and reconciliation frequency. 2. Obtain a statement for the correct entity, account and date. 3. Match invoices, credits, payments and adjustments. 4. Validate missing invoices through normal approval evidence. 5. Resolve unallocated cash, credits and cross-entity items. 6. Check duplicate supplier and duplicate-invoice indicators. 7. Age every exception and assign a named owner. 8. Reconcile adjustments to the ledger and retain sign-off.
Article 26 of the UAE Commercial Companies Law establishes a record-keeping expectation that supports a clear view of transactions and financial position. The control described here is an accounts-payable process, not a substitute for applying the entity's accounting policies to cut-off, accruals or disputed liabilities.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 CFO, Finance and Cash FlowCost Centre Master Data and Expense Allocation Controls for UAE Groups →
 Accounting and BookkeepingPrepaid Expense Amortisation Schedule Controls for UAE Businesses →
 Accounting and BookkeepingSuspense Account Clearing Controls for UAE Finance Teams →
 CFO, Finance and Cash FlowCapital Expenditure Approval and Asset Commissioning Controls in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
Why reconcile supplier statements if the payables ledger already balances?+
The ledger can balance while missing a supplier invoice, credit or allocation. The external statement helps identify differences between the two records.
Can finance post a missing invoice from the supplier statement alone?+
The statement identifies the exception, but posting should follow the normal invoice, purchase, receipt and approval evidence required by the business.
How often should supplier statements be reconciled?+
Use a risk-based cadence. Strategic, high-spend, high-volume or dispute-prone suppliers normally need more frequent review than low-activity vendors.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Find missing supplier items before they reach payment or close
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Find missing supplier items before they reach payment or close
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.