
Supplier Bank Account Change and Payment Beneficiary Validation Controls in the UAE
By Valusage Technical Practice
Editorial responsibility: Valusage Business Advisors Editorial Practice
Direct answer
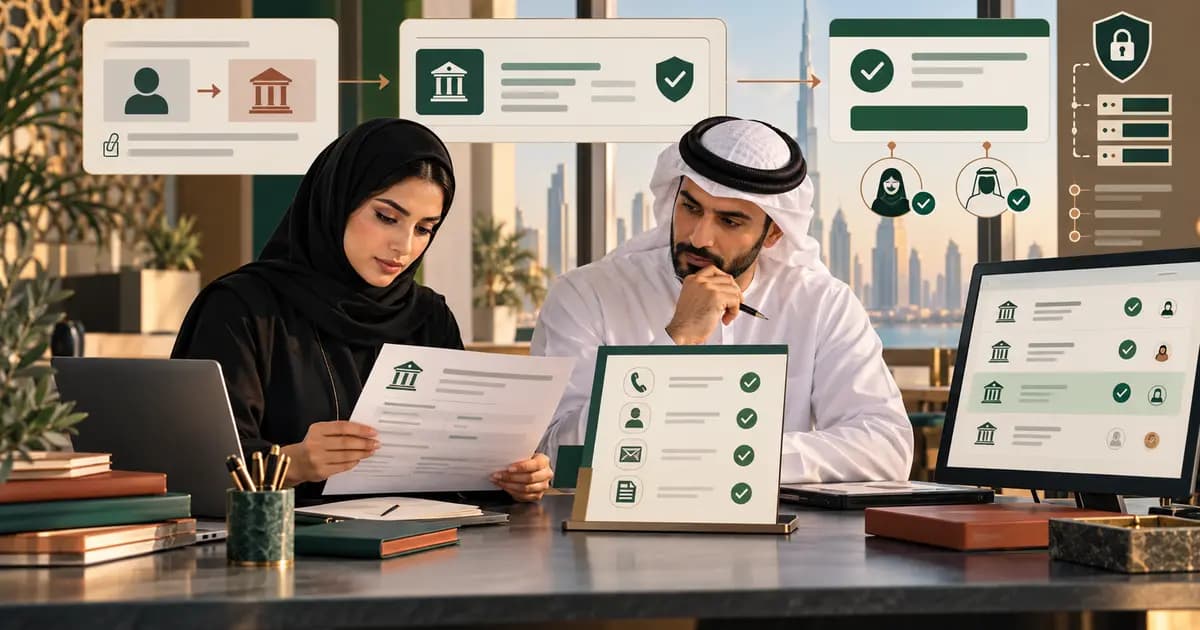
A supplier bank-account change should never flow directly from an email or amended invoice into the payment master. UAE finance teams should record the request, verify the supplier through an independently sourced contact, confirm the legal name and beneficiary details, separate requester, verifier and approver roles, retain the evidence and place the first payment under additional review. Changes should be time-stamped, old details preserved in the audit trail and payment files checked for recent beneficiary amendments before release.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportSupplier bank-detail changes are high-risk because a genuine commercial relationship can be used to make a false request look credible. The safest workflow treats every change as a controlled master-data event rather than routine invoice administration.
Capture the request in a controlled register
Record the supplier, legal entity, request date, requester, stated reason, proposed beneficiary name, bank, account or IBAN, currency, supporting document and intended effective date. Attach the original message or portal submission. Do not overwrite the current master record while verification is still open.
Verify through an independent channel
Contact the supplier using a telephone number, portal or relationship contact already held in approved records—not contact details supplied only in the change request. Confirm the request, beneficiary name, banking jurisdiction and effective date. Record who performed the verification, when it occurred and which independent contact source was used. A reply within the same compromised email thread is not an independent check.
Validate beneficiary and entity alignment
Compare the supplier's legal or trading name, contract party, invoice issuer and requested beneficiary. Differences do not automatically prove fraud, but they require documented explanation and approval. Check the account structure, currency and bank information for obvious inconsistencies, and route third-party or unrelated beneficiary requests for enhanced review rather than treating them as normal master-data maintenance.
Separate duties and preserve history
The person requesting or entering the amendment should not be the only person verifying and approving it. Restrict master-data access, require a named approver and preserve the old and new values with timestamps. Emergency changes should follow a documented exception route with retrospective review; urgency should not remove independent verification.
Control the first payment after change
Flag recently changed beneficiaries in the payment proposal. Reconfirm the supplier, invoice population, amount, currency and beneficiary before releasing the first payment. Compare the payment file with the approved change record and require dual authorisation under the business's banking rules. Avoid combining a bank-detail amendment and an unusual manual payment without additional evidence.
Monitor and respond to exceptions
Review failed callbacks, repeated change requests, changes close to a payment run, beneficiary names that differ from the supplier, requests sent from a new domain, unusual urgency and attempts to bypass the normal approver. If a payment may have been misdirected, escalate immediately to authorised management and the bank, preserve communications and system logs, and follow the organisation's incident-response process.
Supplier bank-change control checklist
1. Log every request before editing master data. 2. Retain the original request and supporting evidence. 3. Verify through an independently sourced contact channel. 4. Confirm supplier, beneficiary, account and currency details. 5. Separate request, verification, entry and approval where practical. 6. Preserve old and new master-data values with timestamps. 7. Apply additional review to the first payment. 8. Monitor recent changes and unresolved verification exceptions.
IAS 7 addresses cash-flow information and the IFRS Conceptual Framework supports relevant, faithfully represented financial information. UAE Commercial Companies legislation requires companies to maintain accounting records sufficient to show transactions and financial position. This article provides an operational-control framework; banks, contracts and individual entities may require additional procedures.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Accounting and BookkeepingFixed Asset Disposal Approval and Proceeds Reconciliation in the UAE →
 CFO, Finance and Cash FlowForeign-Currency Supplier Payment and Bank Fee Reconciliation in the UAE →
 Industry GuidanceHotel OTA Booking, Commission and Payout Reconciliation in the UAE →
 Accounting and BookkeepingSupplier Advance, Purchase Order and Invoice Application Controls in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
How should a UAE business verify a supplier bank-account change?+
Use a contact channel already held in approved records, confirm the request and beneficiary details independently, document the verifier and time, and obtain authorised approval before updating the master.
Should finance trust new bank details shown on a supplier invoice?+
Not by themselves. Treat invoice bank-detail changes as a separate master-data request and complete independent verification and approval before payment.
Why should the first payment after a beneficiary change receive additional review?+
The first payment is the point at which an incorrect or fraudulent change becomes a cash loss, so finance should recheck the approved amendment, invoice population and payment beneficiary before release.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Make every supplier beneficiary change independently verified before payment
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Make every supplier beneficiary change independently verified before payment
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.