
Supplier Advance, Purchase Order and Invoice Application Controls in the UAE
By Valusage Technical Practice
Editorial responsibility: Valusage Business Advisors Editorial Practice
Direct answer
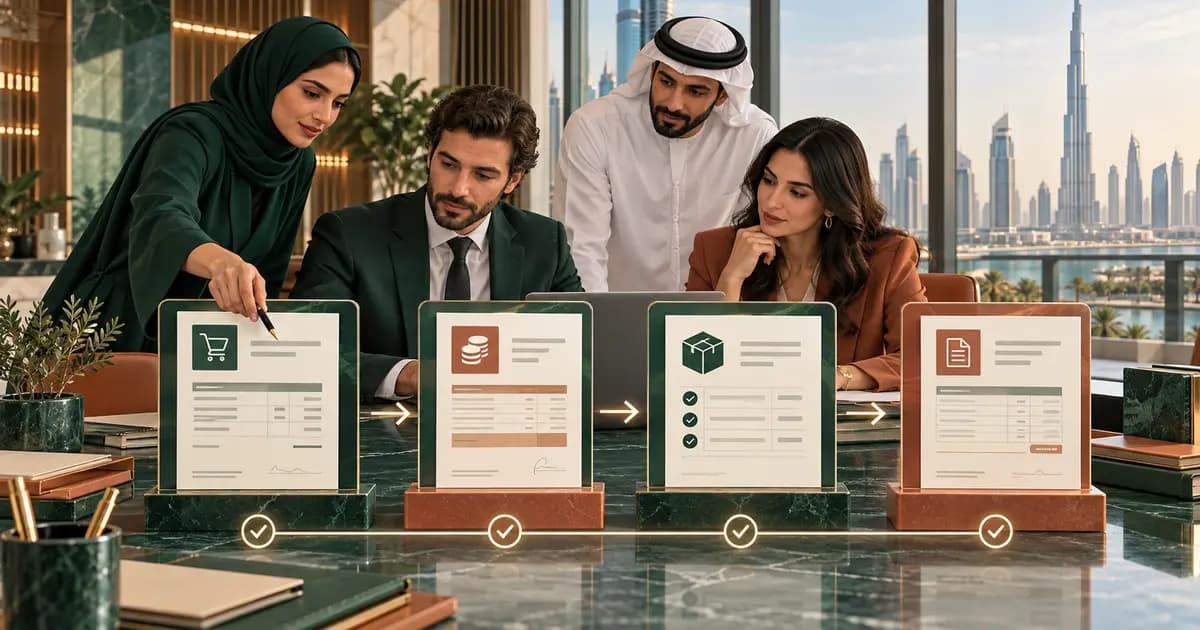
A UAE business paying a supplier in advance should link the approved advance to a specific supplier, legal entity, purchase order or contract, delivery milestone, payment evidence and expected invoice application. Finance should keep an advance register, reconcile goods or services received, apply each supplier invoice against the correct advance, block duplicate settlement and follow up unused or refundable balances. The advance should not disappear into general accounts payable or be treated as a completed purchase without delivery evidence.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportAdvance payments can support procurement, but they move cash before the business has received the full benefit. A purchase-order approval is only the start of the control: finance must show what was paid, what was delivered, how the invoice was applied and what remains recoverable.
Approve the advance against commercial terms
Record the supplier and legal entity, contract or purchase-order reference, amount, currency, reason, milestone, expected delivery date, refund or offset terms and approver. Compare the request with the original purchase commitment. A revised bank account or third-party beneficiary requires its own independent validation before release.
Maintain an advance roll-forward
Use a supplier-level schedule showing opening advance, new payments, invoice applications, refunds, reclassifications and closing balance. Preserve the payment reference and transaction date. Do not net several advances against one supplier without showing which order and invoice each payment belongs to.
Match delivery and invoice evidence
Connect goods receipt or service acceptance to the purchase order and supplier invoice. Confirm the invoice correctly deducts or references the advance and that the remaining balance is calculated once. If the ERP automatically applies advances, review the application report for incorrect supplier, entity, currency or invoice matches.
Prevent a second cash payment
Before an invoice enters the payment proposal, compare the open invoice with the advance register and supplier statement. Flag invoices whose amount equals an earlier deposit, credit notes that have not been applied, and manual payments made outside the approved workflow. A two-way match of invoice and order can miss a prepayment unless the advance is visible to the reviewer.
Age unused and disputed balances
Investigate advances after the expected delivery date, cancelled orders, partial supply and suppliers that have stopped trading. Document whether the balance is to be applied to a later invoice, refunded or escalated. Assign an owner and keep evidence of supplier correspondence. Any accounting write-down or reclassification needs separate, fact-specific review.
Supplier advance control checklist
1. Require an approved commercial reason and purchase reference. 2. Validate beneficiary changes before cash release. 3. Record payment and expected delivery in the advance register. 4. Match receipts and accepted services to the order. 5. Apply each invoice to the correct advance once. 6. Block duplicate payment of already prepaid amounts. 7. Reconcile supplier statement, ledger and bank evidence. 8. Age unused advances and pursue refunds or resolution.
IAS 7 addresses cash movements and the IFRS Conceptual Framework describes concepts for assets and useful financial information. The recognition or impairment of a specific supplier advance depends on contractual rights and facts. This article sets out a process control, not a prescribed accounting treatment.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Accounting and BookkeepingFixed Asset Disposal Approval and Proceeds Reconciliation in the UAE →
 CFO, Finance and Cash FlowForeign-Currency Supplier Payment and Bank Fee Reconciliation in the UAE →
 Industry GuidanceHotel OTA Booking, Commission and Payout Reconciliation in the UAE →
 Accounting and BookkeepingCommercial Lease Rent, Service Charge and Deposit Reconciliation Controls in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What should a supplier advance register contain?+
Show the supplier, entity, order or contract, approval, payment, expected delivery, invoice applications, refunds, owner and closing balance for each advance.
How can finance prevent paying an invoice twice after a supplier advance?+
Make the open advance visible in invoice approval and payment proposals, reconcile the supplier statement and link every invoice application to the original payment reference.
What happens when a supplier advance remains unused?+
Age the balance, confirm the delivery or refund position with the commercial owner and supplier, retain correspondence and escalate any accounting assessment separately.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Keep supplier advances visible until delivery, invoice application or refund
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Keep supplier advances visible until delivery, invoice application or refund
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.