
Fixed Asset Disposal Approval and Proceeds Reconciliation in the UAE
By Valusage Technical Practice
Editorial responsibility: Valusage Business Advisors Editorial Practice
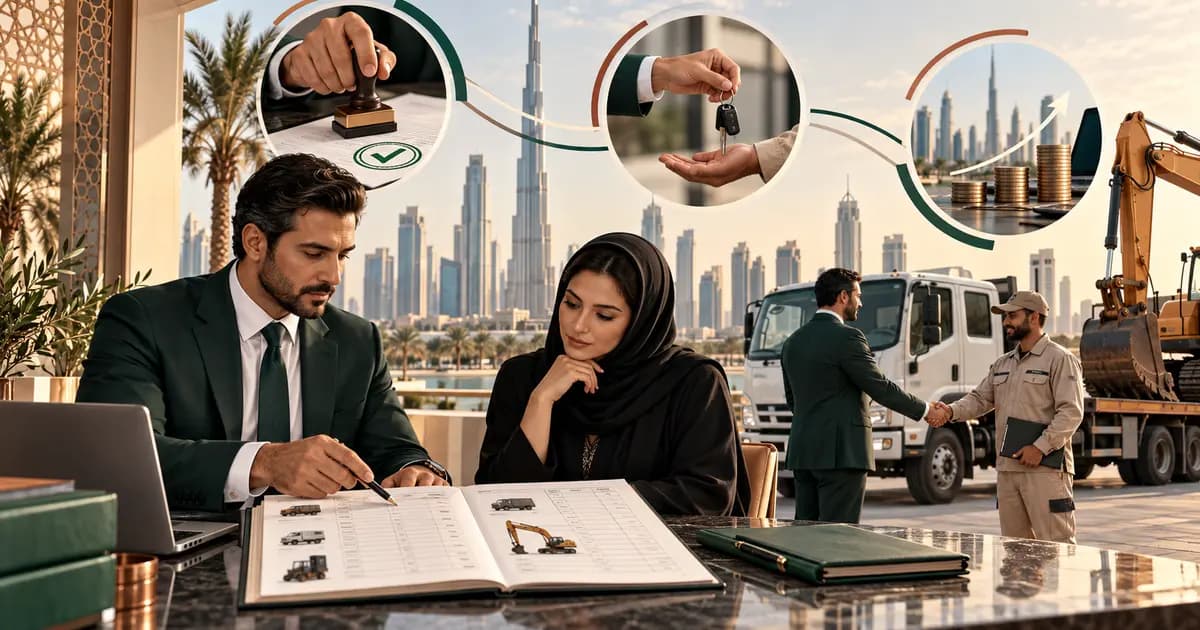
Direct answer
A UAE fixed-asset disposal should start with an approved asset-specific request and end only when custody, sale or scrapping evidence, proceeds, asset-register status and ledger postings agree. Finance should identify the asset and carrying amount, document the reason and sale terms, separate approval from custody transfer, match any buyer receipt to the bank and resolve differences between the disposal schedule and general ledger. A zero-value retirement still needs proof that the asset has left service and the register.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportThe asset register often records acquisitions more reliably than exits. Vehicles, equipment, fit-outs and technology can remain on the books after sale or scrapping, while proceeds arrive in a different period or entity. A disposal file closes the loop between the physical asset and accounting record.
Identify the exact asset and decision
Use the asset tag, serial number, location, custodian, legal owner, acquisition cost, accumulated depreciation and current carrying amount. State whether the asset will be sold, transferred within the group, donated, recycled or scrapped. Require a documented reason and an authorised decision before handover.
Control valuation and sale terms
For a sale, retain the approved price basis, buyer, invoice or sale agreement, payment terms and any related-party assessment. Keep an offer comparison or other evidence proportionate to asset value. The person negotiating a disposal should not alone approve the price and confirm receipt of cash.
Capture physical handover
Record date, condition, recipient, keys or access devices, serial number and signed handover or destruction evidence. Remove system access and insurance cover when appropriate. For group transfers, identify both legal entities and use a separate intercompany record; an internal location change is not automatically an external sale.
Reconcile proceeds and register removal
Match buyer invoice or receipt to the bank deposit by amount, currency and reference. Record unpaid proceeds as an open receivable, not assumed cash. Reconcile the disposal schedule to the fixed-asset register and ledger, including accumulated depreciation and any approved gain or loss calculation. Investigate assets marked inactive operationally but still depreciating.
Review exceptions at period close
Age sold assets with no proceeds, cash receipts with no disposal reference, scrapped assets with no evidence and register removals with no approval. Review insurance claims or trade-in credits as separate transactions. A second reviewer should sign off the schedule and unresolved exceptions.
Asset disposal control checklist
1. Identify asset tag, owner, location and carrying amount. 2. Approve sale, transfer or retirement before handover. 3. Retain price, buyer and contractual evidence where relevant. 4. Document physical transfer or destruction. 5. Match proceeds to bank or record an open receivable. 6. Update the asset register and related access records. 7. Reconcile the disposal schedule to the ledger. 8. Age missing approvals, proceeds and handover evidence.
IAS 16 sets principles for property, plant and equipment, including carrying amounts and depreciation. IAS 7 addresses related cash-flow information. The accounting result for a particular disposal depends on the asset and transaction facts; this article focuses on operational evidence and reconciliation.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 CFO, Finance and Cash FlowForeign-Currency Supplier Payment and Bank Fee Reconciliation in the UAE →
 Industry GuidanceHotel OTA Booking, Commission and Payout Reconciliation in the UAE →
 Accounting and BookkeepingSupplier Advance, Purchase Order and Invoice Application Controls in the UAE →
 Accounting and BookkeepingCommercial Lease Rent, Service Charge and Deposit Reconciliation Controls in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What evidence should support a fixed-asset disposal?+
Keep the approved asset-specific decision, tag and carrying amount, buyer or destruction evidence, handover, invoice, bank receipt or receivable and register and ledger postings.
Can an asset be removed from the register before sale proceeds arrive?+
The timing depends on the transaction facts and accounting policy. The control should separately track physical disposal, any receivable and cash settlement so none is assumed from another.
How should scrapped assets be controlled?+
Require an approved reason, identification of the asset, documented physical destruction or recycling, register removal and independent ledger reconciliation even when proceeds are nil.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Make every asset exit traceable from approval to proceeds and register removal
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Make every asset exit traceable from approval to proceeds and register removal
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.