
Utility Account, Deposit and Meter Reconciliation Controls for UAE Multi-Site Businesses
Editorial responsibility: Valusage Business Advisors Editorial Practice (Editorial Practice)
Direct answer
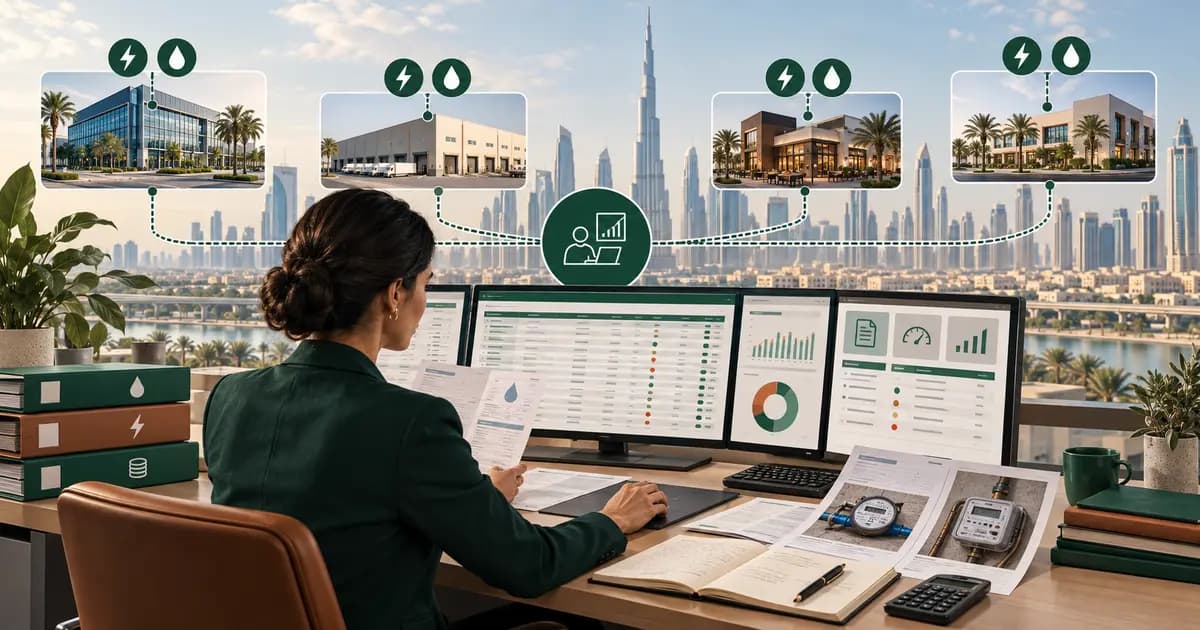
A multi-site utility reconciliation should map every electricity, water or district-cooling account and meter to the correct legal entity, location, cost centre, deposit, billing cycle and payment method. Finance should compare meter and bill periods, investigate missing or duplicate bills, reconcile deposits and open balances, allocate shared charges through an approved driver and track closed accounts until the final bill and deposit refund are resolved.
Advisory decision map
From information to a controlled decision
- 01Question
- 02Evidence
- 03Options
- 04Action
Illustrative evidence trend
Decision supportUtility costs become difficult to control when sites open, relocate or close and account ownership does not follow the operating change. A complete register helps finance distinguish consumption, timing, deposits, shared charges and unresolved provider balances.
Build the account and meter register
Record the provider, account number, meter, legal entity, site, landlord or tenant responsibility, service type, activation date, billing cycle, deposit, payment method and operational owner. Keep closed accounts visible until their final balance and deposit are settled.
Match the service period to the site
Review the bill period, meter reading, opening and closing status and location. Investigate overlaps, gaps, estimated readings, duplicate accounts and bills issued after a site closed. Do not allocate a bill to a department solely because it was paid from that department's bank account.
Reconcile deposits separately
Maintain a deposit schedule with payment evidence, account, amount, currency, activation date and expected recovery event. Match deposit top-ups, transfers and refunds to the correct account. Avoid writing off an old deposit merely because the operating site changed.
Control missing bills and accruals
Use the billing calendar to identify missing periods before close. Estimate an accrual from an approved basis such as recent consumption, meter data or contract information and replace it when the actual bill arrives. Track estimate-to-actual differences to improve the next close.
Allocate shared utility costs transparently
Where one account serves several departments or sites, document the driver, source data, review frequency and approver. Use meter data where available. If another driver is used, explain why it reasonably represents consumption and keep it consistent until facts change.
Review exceptions across locations
Compare consumption and cost per relevant operational measure, but treat movements as questions rather than proof of waste. Weather, occupancy, opening hours, equipment, tariffs and reading corrections can change the result. Assign operational review to a named owner.
Utility reconciliation checklist
1. Map every account and meter to entity and site. 2. Record deposits separately from monthly charges. 3. Confirm bill and meter-reading periods. 4. Detect missing, duplicate and post-closure bills. 5. Reconcile bills, payments and provider balances. 6. Support accruals and replace them with actual bills. 7. Approve shared-cost allocation drivers. 8. Track closed accounts through final refund.
IAS 7 addresses cash-flow information and the Conceptual Framework addresses faithful representation. Classification, accrual and allocation decisions remain dependent on the entity's facts and reviewed accounting policy.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Accounting and BookkeepingCustomer Deposit and Unapplied Cash Reconciliation Controls in the UAE →
 Accounting and BookkeepingSupplier Return, Debit Note and Credit Reconciliation Controls in the UAE →
 Industry GuidanceVendor Rebate Accrual and Claim Reconciliation Controls for UAE Distributors →
 Accounting and BookkeepingAccrual Ageing and Reversal Controls for UAE Month End Close →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What should a multi-site utility register include?+
Include provider, account, meter, entity, location, service, deposit, billing cycle, payment method, activation or closure date and responsible owner.
How should missing utility bills be handled at month end?+
Identify the missing period, prepare a supported accrual using an approved basis, and compare it with the actual bill when received.
How should utility deposits for closed sites be controlled?+
Keep the account and deposit open in the register until the final bill, transfer or refund is evidenced and reconciled to the ledger.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Make every utility account, meter and deposit traceable by site
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Make every utility account, meter and deposit traceable by site
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.