
Customer Deposit and Unapplied Cash Reconciliation Controls in the UAE
Editorial responsibility: Valusage Business Advisors Editorial Practice (Editorial Practice)
Direct answer
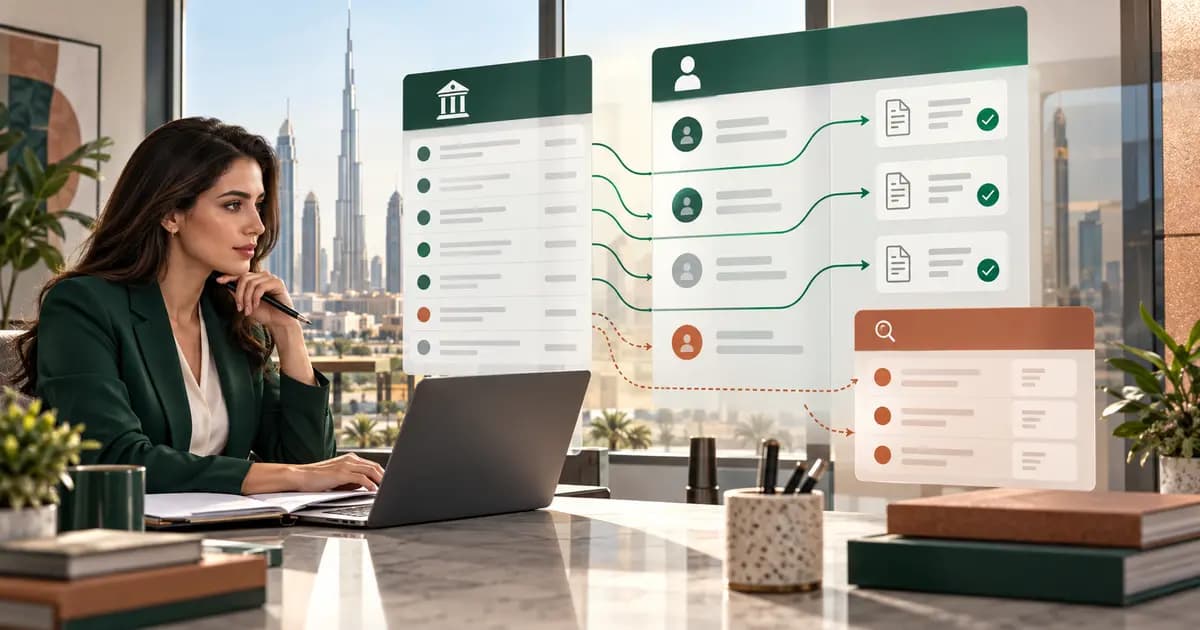
A customer-deposit and unapplied-cash reconciliation should match each bank receipt to the paying party, legal entity, customer account, contract or order, invoice where applicable, currency, value date and approved allocation. Finance should keep unidentified receipts in a controlled suspense population, age every open item, prevent cash allocation from determining revenue recognition and clear deposits only when the supported commercial event or authorised refund occurs.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportIncoming cash does not become reliable accounting evidence merely because it appears in the bank. The payer name may differ from the customer, one receipt may cover several invoices, or money may arrive before an invoice or delivery. A structured allocation process protects cash reporting, receivables and customer balances.
Capture the bank receipt completely
Record the legal entity, receiving bank account, value date, currency, amount, bank reference, payer name and available remittance detail. Use a unique receipt reference from the bank import through final allocation. Restrict manual edits to bank-source fields.
Identify the commercial owner
Match the payer to the customer or group account using approved master data and supporting communication. Where a third party pays, retain evidence linking the payer, customer and transaction. Assign unclear items to a named sales or collections owner instead of leaving finance to guess.
Separate deposits from invoice settlement
Classify whether the receipt relates to an issued invoice, an advance payment, a refundable deposit, a security amount or another supported purpose. Do not force a receipt against the oldest invoice solely to clear the bank reconciliation. The allocation should follow evidence and approved policy.
Keep revenue recognition independent
IFRS 15 focuses on contracts and performance obligations. Receipt of cash does not by itself prove that revenue has been earned. Finance should connect customer deposits to the contract, order, delivery or service evidence and maintain any resulting liability or receivable according to the entity's reviewed accounting policy.
Age unapplied and unidentified cash
Age items from the bank value date and report the amount, customer or suspected payer, reason, owner and next action. Escalate old items, repeat payers without remittance and receipts held across reporting periods. A suspense balance is a temporary control point, not a permanent classification.
Control reallocations and refunds
Require approval and an audit trail for moving cash between customers, invoices or legal entities. Before refunding, confirm the original receipt, payer, contractual basis, bank details and segregation of duties. Prevent a refund where the receipt was already charged back or applied elsewhere.
Customer cash allocation checklist
1. Import complete bank receipt data. 2. Assign one unique receipt reference. 3. Identify payer, customer and legal entity. 4. Classify invoice settlement, advance or deposit. 5. Keep revenue assessment separate from cash receipt. 6. Age every unapplied item with an owner. 7. Approve reallocations and refunds independently. 8. Reconcile the cash register to bank and ledger.
This article provides management-control guidance. Contract liabilities, revenue, refunds and presentation require fact-specific accounting and contractual review.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Accounting and BookkeepingSupplier Return, Debit Note and Credit Reconciliation Controls in the UAE →
 Industry GuidanceUtility Account, Deposit and Meter Reconciliation Controls for UAE Multi-Site Businesses →
 Industry GuidanceVendor Rebate Accrual and Claim Reconciliation Controls for UAE Distributors →
 Accounting and BookkeepingAccrual Ageing and Reversal Controls for UAE Month End Close →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What is unapplied cash?+
It is a bank receipt that has not yet been supported and allocated to the correct customer, invoice, deposit, contract or other approved purpose.
Should finance apply an unidentified receipt to the oldest invoice?+
No. Allocation should follow payer, remittance and commercial evidence rather than an assumption made only to clear the reconciliation.
Does receiving a customer deposit create revenue?+
Not by itself. Revenue depends on the contract, performance and the entity’s reviewed accounting policy, not only on when cash is received.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Allocate every receipt through evidence before clearing customer balances
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Allocate every receipt through evidence before clearing customer balances
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.