Suspense Account Clearing Controls for UAE Finance Teams
Editorial responsibility: Valusage Business Advisors Editorial Practice (Editorial Practice)
Direct answer
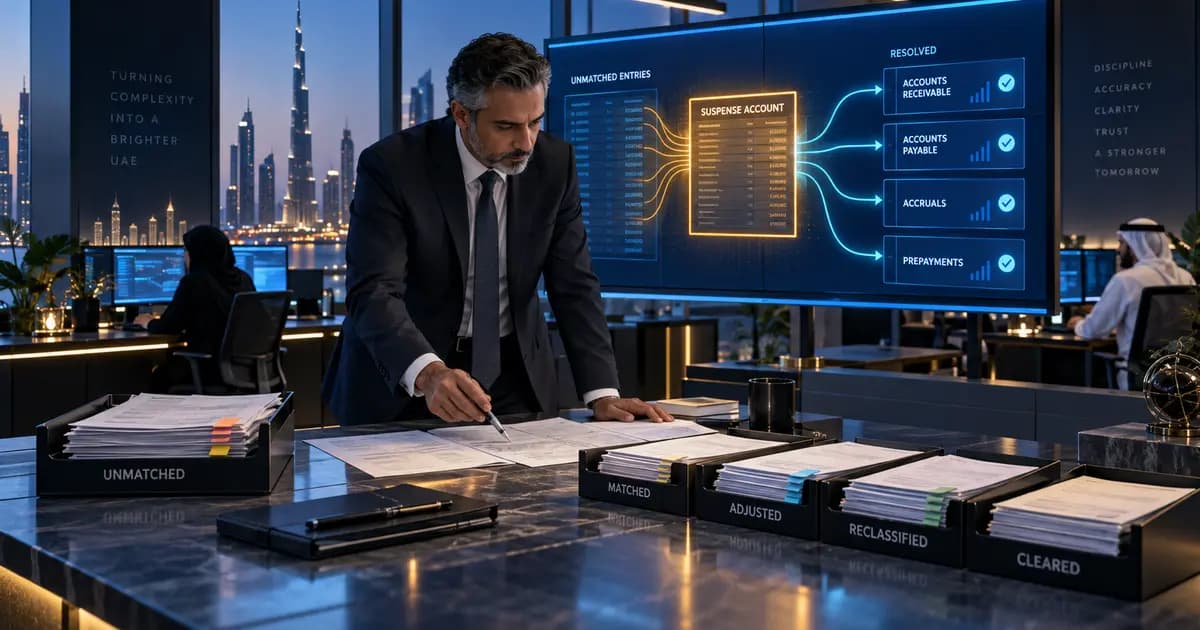
A suspense account should be a short-term controlled holding point, not a permanent destination. Every entry needs a source, reason, owner and resolution date; finance should reconcile the account at each close, age unresolved items, approve reclassifications independently and escalate items that breach defined value or time limits. Recurring causes should be fixed at the originating process.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportSuspense accounts are useful when a transaction cannot yet be classified reliably, but they become dangerous when unidentified entries accumulate without ownership. A disciplined clearing control protects the accuracy of the balance sheet while allowing finance time to obtain missing evidence.
Define permitted use
Document which transaction types may enter each suspense account, who can post, required references and maximum clearing time. Separate bank receipts, payment-interface errors, payroll exceptions and system-migration differences where volume justifies distinct accounts. Do not use one generic code to absorb budget variances, balancing entries or unexplained write-offs.
Require minimum evidence at entry
Capture source system, transaction date, value date, amount, currency, entity, counterparty where known, preparer and reason for temporary classification. Attach bank, interface, payroll or operational evidence. An entry without a meaningful narrative and reference should be rejected or immediately escalated.
Reconcile the population at every close
Roll forward opening items, new postings, cleared amounts and the closing balance. Match the account to the subledger, bank interface or other originating report. Confirm that clearing entries remove the original item and do not create an offsetting unexplained balance. Review debit and credit items separately because net totals can hide large exceptions.
Age by unresolved date and risk
Use ageing bands tied to the control policy, such as current, approaching deadline and overdue. Add value, transaction type, fraud sensitivity, customer or supplier impact and reporting materiality. A small recurring item can reveal a broken interface even if it is not individually material.
Resolve through supported reclassification
The investigator should identify the correct account and obtain evidence from the responsible team. A reviewer independent of the original posting should approve material or unusual reclassifications. Do not clear items to miscellaneous income or expense merely to meet a close deadline. If evidence remains unavailable, record the accounting judgement and escalation under the applicable policy.
Prevent recurrence
Classify root causes: incomplete payment references, outdated master data, interface mapping, bank timing, duplicate imports, payroll setup or unclear process ownership. Track repeat counts and values. Fix the source rule, form or system mapping when the same exception reappears rather than relying on faster manual clearing.
Report management exceptions
The close pack should show opening and closing suspense balances, new and cleared volumes, overdue items, oldest entry, material exceptions and root-cause actions. IAS 1 sets overall presentation requirements for financial statements, while IAS 8 addresses the selection and consistent application of accounting policies and correction of errors. The operational register supports those outcomes but does not replace accounting judgement.
Suspense account checklist
1. Restrict allowed uses and posting access. 2. Require a source, reason, owner and target clearing date. 3. Reconcile opening, movements and closing balance. 4. Review gross debit and credit populations. 5. Age items and escalate overdue or high-risk exceptions. 6. Approve supported reclassifications independently. 7. Track recurring root causes to process owners. 8. Retain close review and evidence of final clearance.
This guide addresses finance-process governance. The correct classification, recognition and correction of any specific entry depends on its facts and the business's applicable reporting framework.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 CFO, Finance and Cash FlowCost Centre Master Data and Expense Allocation Controls for UAE Groups →
 Accounting and BookkeepingPrepaid Expense Amortisation Schedule Controls for UAE Businesses →
 Accounting and BookkeepingSupplier Statement Reconciliation and Missing Invoice Controls in the UAE →
 CFO, Finance and Cash FlowCapital Expenditure Approval and Asset Commissioning Controls in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
How long should an item remain in a suspense account?+
The business should define a short risk-based limit. Every item needs a target date, and overdue or high-value entries should be escalated before close approval.
Can suspense items be netted for reporting?+
A net total can hide significant debit and credit exceptions. Review the gross populations and classify each item based on its supporting facts.
Who should approve suspense-account clearance?+
Use review independent of the original posting for material, unusual or judgemental reclassifications, with evidence retained for the close file.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Turn unexplained balances into owned, evidenced actions
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Turn unexplained balances into owned, evidenced actions
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.