Prepaid Expense Amortisation Schedule Controls for UAE Businesses
Editorial responsibility: Valusage Business Advisors Editorial Practice (Editorial Practice)
Direct answer
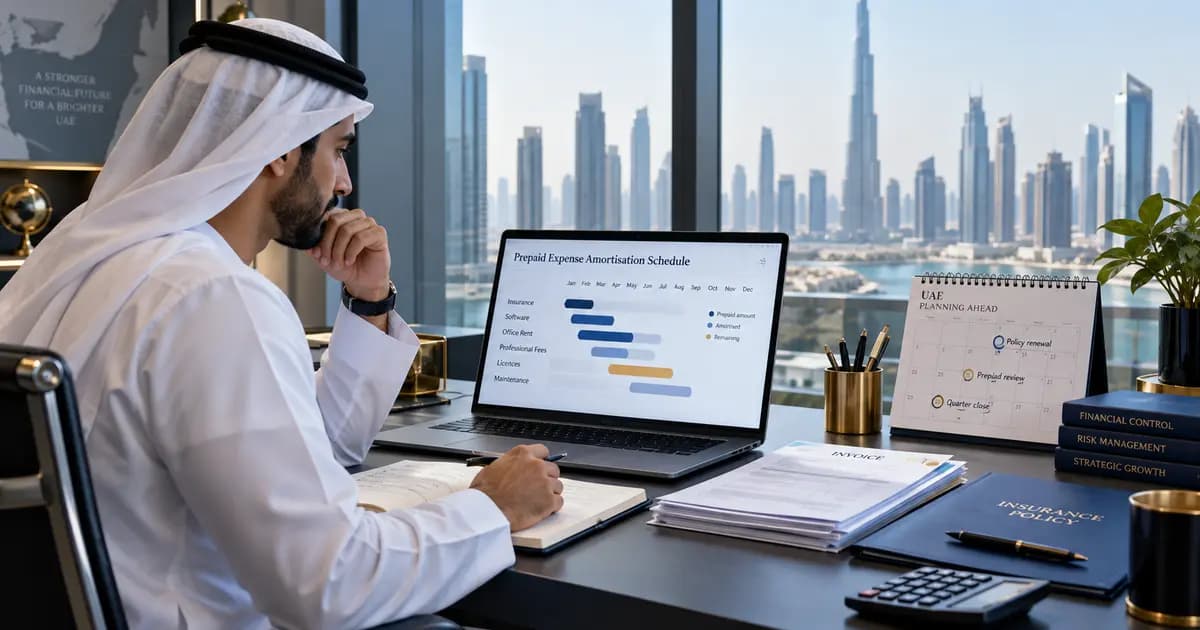
A controlled prepaid-expense schedule should identify every advance payment, document the benefit period and responsible owner, calculate the monthly release under an approved policy, reconcile opening additions and amortisation to the ledger, and investigate expired, duplicated or unsupported balances before each close. The schedule should show what remains, why it remains and when it will be released or recovered.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportPrepaid expenses can look harmless because cash has already left the bank. Yet unsupported prepayments can overstate assets, delay expenses and hide missed cancellations or supplier credits. UAE finance teams need one schedule that connects the original commitment to the service period, monthly accounting and final closure.
Define what belongs on the schedule
Include payments made before the related goods or services are received, such as annual insurance, software subscriptions, maintenance contracts, permits, retainers and advance rentals where the facts support prepaid treatment. Record the legal entity, supplier, contract, invoice, payment, start date, end date, currency, department, ledger account and owner. Deposits, advances for inventory and capital-project payments should remain separately identifiable because they may follow different accounting and operational processes.
Capture the benefit period from evidence
Use the signed contract, renewal notice, policy document, licence or other support to establish when the benefit begins and ends. Do not assume that invoice date, payment date and service start date are the same. Document partial periods, free months, implementation phases, cancellation rights and expected credits. If the period is uncertain, escalate it instead of selecting a convenient release date.
Govern the amortisation rule
Define whether the business releases amounts daily, monthly or using another supportable method. Protect formulas and identify manual overrides. The rule should be applied consistently to similar items, while genuine differences remain documented. IAS 8 describes accounting policies as the principles, bases, conventions, rules and practices used in preparing financial statements; the practical schedule should therefore follow the approved policy rather than change method without review.
Reconcile the monthly roll-forward
Start with the prior closing balance, add new supported prepayments, deduct the period expense, record approved credits or write-offs and arrive at the current closing balance. Reconcile the schedule total to each general-ledger account and explain every difference. Review journals posted directly to the ledger, negative prepayments, credit balances and additions without payment evidence.
Challenge ageing and expiry
Age the remaining balance by expected release date, not only by invoice date. Identify contracts that ended, services that were cancelled, duplicate renewals, suppliers that owe refunds and balances with no current owner. Ask operations to confirm whether the benefit is still being received. A long-outstanding item should not remain an asset merely because the original schedule was never updated.
Connect renewals to cash control
Use the register to provide notice before renewal or cancellation dates. Confirm whether the service is still required, whether pricing changed and which budget owner approved renewal. This turns the schedule into a forward control over cash commitments rather than a backward-looking accounting list.
Prepaid expense close checklist
1. Reconcile the opening schedule to the prior close. 2. Match additions to approved contracts, invoices and payments. 3. Confirm service start and end dates with evidence. 4. Recalculate automated and manual amortisation. 5. Reconcile schedule totals to the ledger by entity and account. 6. Investigate expired, negative and ownerless balances. 7. Record renewal, cancellation, refund and write-off actions. 8. Retain reviewer sign-off and exception closure evidence.
The UAE Commercial Companies Law requires companies to keep accounting records that give a clear picture of their transactions and financial position. This operational guide supports that record trail. Recognition, measurement and presentation should still follow the entity's applicable reporting framework and specific facts.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 CFO, Finance and Cash FlowCost Centre Master Data and Expense Allocation Controls for UAE Groups →
 Accounting and BookkeepingSupplier Statement Reconciliation and Missing Invoice Controls in the UAE →
 Accounting and BookkeepingSuspense Account Clearing Controls for UAE Finance Teams →
 CFO, Finance and Cash FlowCapital Expenditure Approval and Asset Commissioning Controls in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What should a prepaid expense schedule contain?+
Record the entity, supplier, contract and invoice, payment, service period, currency, owner, ledger account, release method, monthly movement and remaining balance.
Should a prepaid expense start amortising on the payment date?+
Not automatically. The release should follow the supported period in which the related benefit is received, which may differ from the invoice and payment dates.
How should old prepaid balances be reviewed?+
Confirm that the benefit still exists, inspect expiry and cancellation terms, seek supplier credits or refunds where relevant, and approve any correction or write-off with evidence.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Make every prepaid balance traceable to a current benefit
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Make every prepaid balance traceable to a current benefit
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.