
Corporate Insurance Policy, Premium and Claim Reconciliation Controls in the UAE
By Valusage Technical Practice
Editorial responsibility: Valusage Business Advisors Editorial Practice
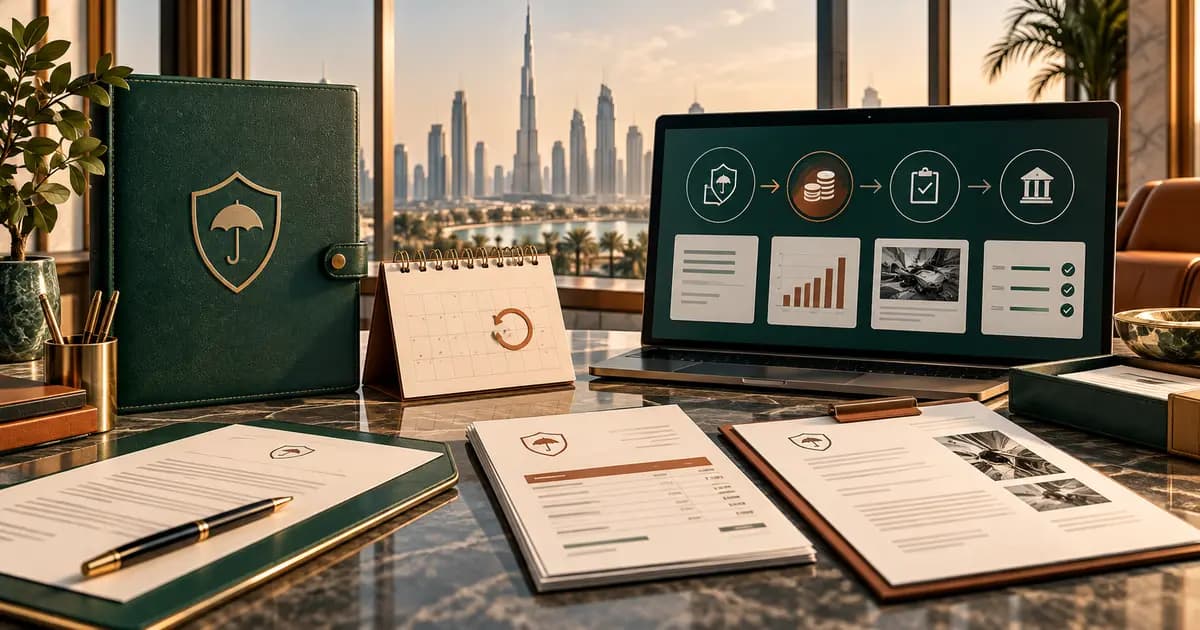
Direct answer
A UAE business should maintain one insurance register that links each active policy to the insured entity, coverage period, premium and instalment schedule, broker or insurer invoice, payment, endorsement, cancellation, refund and claim status. Finance should reconcile the register to bank activity, prepayment or expense schedules, open payables and any separately reviewed claim receivable. A claim submission is not the same as an approved settlement, and a policy renewal should not silently create a duplicate premium or leave an old refund unresolved.
Management decision map
From information to a controlled decision
- 01Measure
- 02Forecast
- 03Decide
- 04Act
Illustrative evidence trend
Decision supportInsurance records often sit across operations, HR, brokers and finance. Without one controlled register, a business can renew overlapping cover, miss an instalment, expense the wrong period or leave refunds and claims outside the month-end review.
Build a complete policy register
Record policy number, insurer, broker, insured legal entity, coverage type, insured asset or employee population, start and end dates, currency, premium, taxes or fees, instalment dates and responsible owner. Link the signed policy, schedule and endorsements. A broker summary should not replace the underlying insurer evidence.
Match premiums to approved cover
Compare each invoice or debit note with the approved policy terms and coverage period. Separate base premium, policy fees and later endorsements. Match payments to the correct policy and instalment rather than clearing a broker account in aggregate. Flag duplicate invoices, payments made for the wrong entity and renewals raised before the prior policy is closed.
Reconcile period allocation and cash
Maintain a roll-forward showing opening prepayment or payable, new premiums, period allocation, payments, credits, refunds and closing balance. Reconcile the schedule to the bank and general ledger. The accounting treatment and allocation period depend on the contract and policy; retain the reviewed basis instead of copying a prior-year entry automatically.
Track endorsements, cancellations and refunds
Record additions, removals, revised sums insured and policy cancellations with their effective dates. When a credit is expected, show the calculation, insurer acknowledgement, credit note, bank receipt and ledger clearance separately. Do not net an unidentified refund against the next renewal merely to clear the account.
Keep claim stages distinct
Track incident date, claim reference, submitted amount, documents, insurer assessment, approved settlement, deductions, receipt and closure. A submitted or estimated claim should not be treated as cash or final approval. Any recognition decision requires separate fact-specific accounting review.
Insurance reconciliation checklist
1. List every active policy by legal entity and coverage period. 2. Match premiums and instalments to approved policy evidence. 3. Reconcile invoices, payments, credits and refunds. 4. Roll forward the related ledger balances each month. 5. Record every endorsement and cancellation effective date. 6. Separate submitted, assessed, approved and paid claims. 7. Age overdue refunds, credits and claim settlements. 8. Review renewals for overlap, gaps and duplicate payment.
IAS 7 addresses cash-flow information and the IFRS Conceptual Framework provides concepts for useful financial reporting. Specific premium allocation, reimbursement or claim recognition depends on policy terms and facts. This is a finance-control framework, not an insurance-coverage or accounting conclusion.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Accounting and BookkeepingDamaged and Expired Inventory Quarantine, Write-Off and Disposal Controls in the UAE →
 Accounting and BookkeepingEmployee Attendance, Overtime and Payroll Input Reconciliation Controls in the UAE →
 Business Process and AutomationSupplier Onboarding and Vendor Master-Data Approval Controls in the UAE →
 Accounting and BookkeepingFixed Asset Disposal Approval and Proceeds Reconciliation in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What should a UAE corporate insurance register contain?+
Include the insurer, broker, policy number, insured entity, coverage period, premium schedule, invoices, payments, endorsements, refunds, claim stages, owner and supporting documents.
Should an insurance claim be recorded as settled when it is submitted?+
No. Submission, assessment, approval and cash settlement are different stages. Keep them separate and obtain fact-specific accounting review before recognising any claim-related balance.
How should an insurance premium refund be controlled?+
Link the expected refund to the endorsement or cancellation, insurer calculation, credit note, bank receipt and ledger clearance, and age it until all records agree.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Connect every insurance policy, premium, refund and claim to cash and the ledger
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Connect every insurance policy, premium, refund and claim to cash and the ledger
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.