
Inter-Branch Inventory Transfer Reconciliation Controls for UAE Businesses
By Valusage Technical Practice
Editorial responsibility: Valusage Business Advisors Editorial Practice
Direct answer
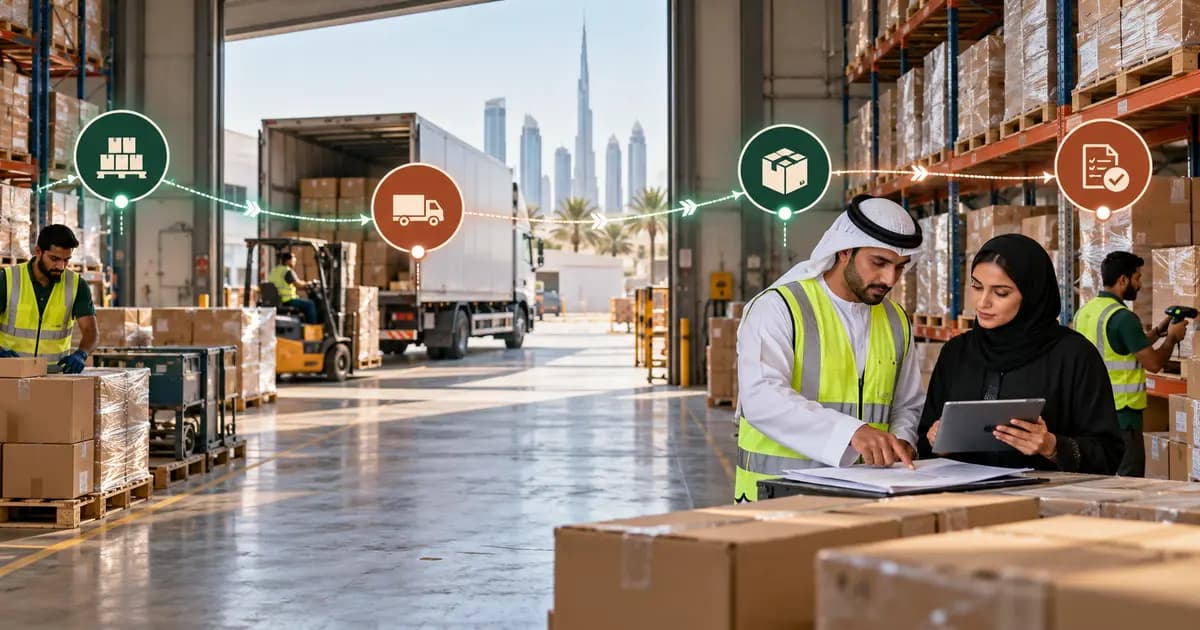
An inter-branch inventory transfer reconciliation should connect every approved transfer request to the dispatch document, item and quantity, source-location issue, transport evidence, goods-in-transit status, destination receipt, accepted differences and both locations’ inventory postings. UAE multi-location businesses should use one transfer reference, block silent quantity edits, age in-transit items, investigate loss or damage promptly and reconcile source issues, destination receipts and the inventory ledger before period close.
Advisory decision map
From information to a controlled decision
- 01Question
- 02Evidence
- 03Options
- 04Action
Illustrative evidence trend
Decision supportTransfers between branches or outlets do not create an external purchase or sale, but they can create stock loss, duplicate quantities and misleading location margins when dispatch and receipt records do not agree. A transfer-level control keeps ownership, custody and ledger movement connected.
Start with an authorised transfer request
Record the requesting and sending locations, legal entity, item, unit of measure, quantity, reason, required date, approver and unique transfer reference. Check available stock and restricted or batch-controlled items before release. Emergency transfers should follow an approved exception route rather than bypassing the register.
Control dispatch at the source location
The source team should confirm picked quantity, batch or serial details where relevant, packing condition, dispatch date, carrier or driver and handover evidence. Post the source issue against the same transfer reference. Prevent users from changing the destination or quantity after dispatch without a visible amendment and approval.
Maintain a goods-in-transit view
Record every dispatched but unreceived transfer with expected arrival date and current owner. Age items by route, value and days outstanding. An item should not disappear from the source without appearing either at the destination or in a controlled in-transit status. Review items crossing month-end separately for cut-off.
Confirm receipt at the destination
The receiving location should record receipt date, quantity, condition, batch or serial information and exceptions. Require independent acknowledgement rather than an automatic receipt copied from dispatch. Record shortages, overages, substitutions and damage against the original transfer; do not silently change the received quantity to make the transfer close.
Reconcile system and physical records
Match the transfer register to source issues, in-transit balances, destination receipts and inventory ledgers by item and location. Investigate transfers marked received in one system but open in another, duplicate receipts, unit-of-measure errors, negative stock and manual journals. Periodic physical counts should test whether repeated transfer differences are accumulating at specific routes or sites.
Close and learn from exceptions
Assign shortages, damage, delayed receipt, rejected goods and posting errors to an owner. Preserve investigation and approval for any adjustment. Report recurring differences by item, location, route and responsible process so management can address packing, transport, receiving or system-design weaknesses.
Inter-branch transfer control checklist
1. Use one approved reference for every transfer. 2. Validate item, unit, quantity and destination before dispatch. 3. Capture source issue and handover evidence. 4. Age all goods-in-transit balances. 5. Require independent destination receipt. 6. Record shortages, damage and substitutions visibly. 7. Reconcile both locations and the inventory ledger. 8. Investigate repeated route and location differences.
IAS 2 addresses inventory measurement and the recognition of inventory-related expense. The IFRS Conceptual Framework supports useful information that faithfully represents transactions. The treatment of a specific loss, damage or location movement depends on the facts and approved accounting policy. This article provides an operational control framework.
About the author
Haris Arif is Head of Finance and Investment. He is a finance and investment leader with experience across multi-entity businesses in technology, F&B and hospitality. He writes practical insights on financial control, management reporting, working capital, tax readiness and finance transformation for UAE founders, CFOs, investors and management teams.
Connect with Haris Arif on LinkedIn: https://www.linkedin.com/in/harisarifofficial/
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Accounting and BookkeepingFixed Asset Disposal Approval and Proceeds Reconciliation in the UAE →
 CFO, Finance and Cash FlowForeign-Currency Supplier Payment and Bank Fee Reconciliation in the UAE →
 Industry GuidanceHotel OTA Booking, Commission and Payout Reconciliation in the UAE →
 Accounting and BookkeepingSupplier Advance, Purchase Order and Invoice Application Controls in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What should an inter-branch inventory transfer reconciliation include?+
Include the approved request, source dispatch, transport handover, in-transit status, destination receipt, accepted differences, inventory postings and final closure evidence.
How should goods in transit between UAE branches be controlled?+
Use a dated in-transit register with expected receipt, value, route and owner, then age and investigate every transfer that remains open beyond its expected arrival.
Should the destination automatically receive the quantity dispatched?+
No. The destination should confirm actual quantity and condition independently, with differences recorded and resolved against the original transfer.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Make every stock transfer traceable from dispatch to destination receipt
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Make every stock transfer traceable from dispatch to destination receipt
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.