Purchase Price Variance and Supplier Cost Change Controls for UAE Businesses
By Valusage Technical Practice
Editorial responsibility: Valusage Business Advisors Editorial Practice
Direct answer
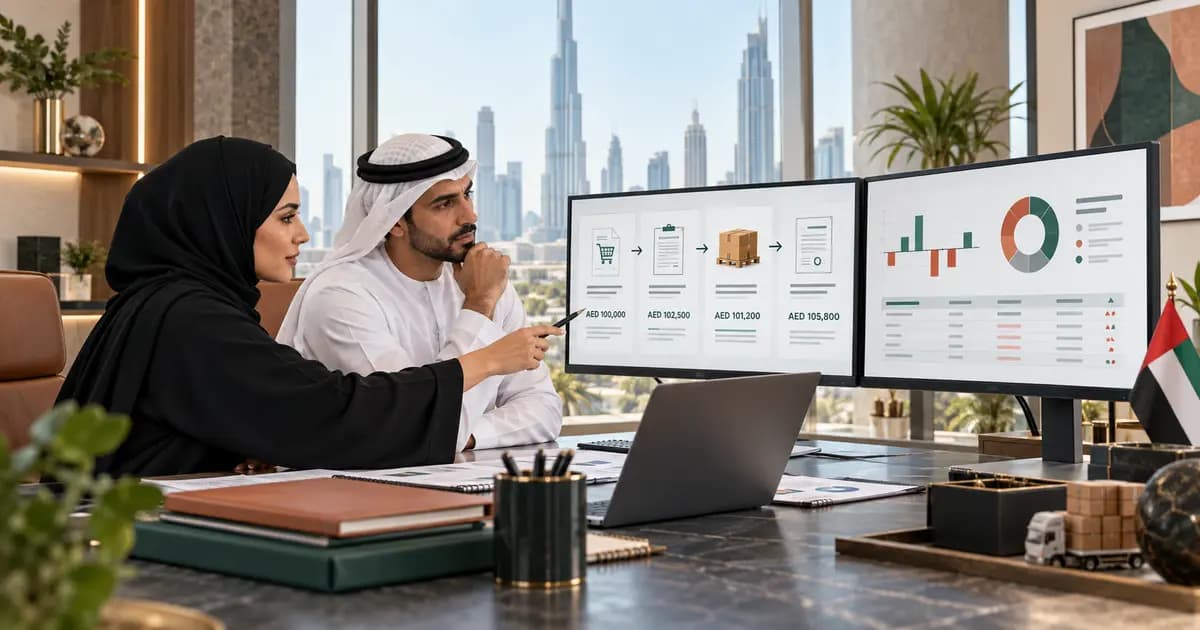
A controlled purchase-price variance process should compare the approved purchase-order price with the agreed supplier basis, received quantity, invoice price and current item or contract master. Finance and procurement should classify every material variance, approve valid price changes before payment, prevent retrospective master-data edits and assign recurring causes to an owner. The goal is not to eliminate every variance. It is to explain each variance before it distorts inventory cost, margin or cash expectations.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportPurchase-price variance becomes useful when it explains why expected cost and actual cost differ. A single total does not tell management whether the cause is a valid supplier increase, an expired quotation, a unit-of-measure error, an incorrect receipt or an invoice outside agreed terms.
Define the comparison basis
Choose one approved baseline for each purchase. It may be a contract price, accepted quotation, framework rate or authorised purchase-order line. Record the currency, unit of measure, effective date, freight basis and tax treatment used in the comparison. Do not compare an invoice with an outdated catalogue value and call the difference a supplier variance.
Separate price from quantity and timing
Calculate price variance on comparable quantities and units. Record quantity differences, partial receipts, returns, exchange-rate effects, freight and other landed-cost components separately. This prevents operational issues from being buried inside a price label.
Control supplier and item master changes
Require an approved request for changes to supplier pricing, item units, pack sizes or purchasing conditions. Retain the source and effective date. The person requesting a price change should not be the only person approving the change or resolving the resulting invoice exception.
Review the three records together
Use the purchase order, receipt evidence and supplier invoice as one control set. Where a valid price change occurred after the order, record the authorised amendment rather than changing history without evidence. Where the invoice is wrong, keep it in the exception queue until procurement and the supplier resolve it.
Analyse recurring causes
Group variances by supplier, item, buyer, category and reason. Repeated small differences can reveal weak master data, late contract updates, inconsistent units or uncontrolled rush buying. Management should focus on the causes that recur or materially affect cost and margin.
Connect the result to accounting
Reconcile approved purchase-price differences to inventory, cost of sales, expense or accrual records as appropriate to the underlying transaction. IAS 2 addresses the measurement of inventories. The exact accounting conclusion depends on the facts and applicable policy; this article describes operational evidence and review controls, not a prescribed journal entry.
Purchase-price variance checklist
1. Record the approved price source and effective period. 2. Confirm currency, unit and quantity are comparable. 3. Separate price, quantity, timing and freight effects. 4. Protect supplier and item master changes. 5. Match order, receipt and invoice evidence. 6. Approve valid amendments before payment. 7. Assign every material exception to an owner. 8. Analyse recurring causes and margin impact.
These recommendations are editorial management-control guidance. UAE Commercial Companies legislation requires companies to keep accounting records that accurately show transactions and disclose financial position. The appropriate accounting treatment still requires fact-specific review.
Editorial practice
Prepared by Valusage Technical Practice. Editorial responsibility rests with Valusage Business Advisors Editorial Practice under the published editorial and corrections policy.
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Accounting and BookkeepingConsignment Inventory Ownership, Count and Settlement Controls in the UAE →
 Accounting and BookkeepingMaintenance Work Order, Service Receipt, Accrual and Invoice Controls in the UAE →
 Industry GuidancePromotional Discount, Coupon and Co-Funding Reconciliation Controls in the UAE →
 Industry GuidanceReturnable Packaging, Crate and Pallet Deposit Reconciliation Controls in the UAE →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What is purchase price variance?+
It is the difference between an approved purchasing price basis and the comparable actual price, after quantity, unit, currency and timing are aligned.
Should every supplier price difference be blocked?+
No. The business should use documented thresholds and route material or unexplained differences for review before approval and payment.
Who should own recurring price variances?+
Procurement, finance and the relevant budget or category owner should assign the root cause and action to a named owner.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Make supplier cost changes traceable before they affect margin
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Make supplier cost changes traceable before they affect margin
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.