
Goods-in-Transit, Receipt and Cut-Off Reconciliation Controls for UAE Importers
By Valusage Technical Practice
Editorial responsibility: Valusage Business Advisors Editorial Practice
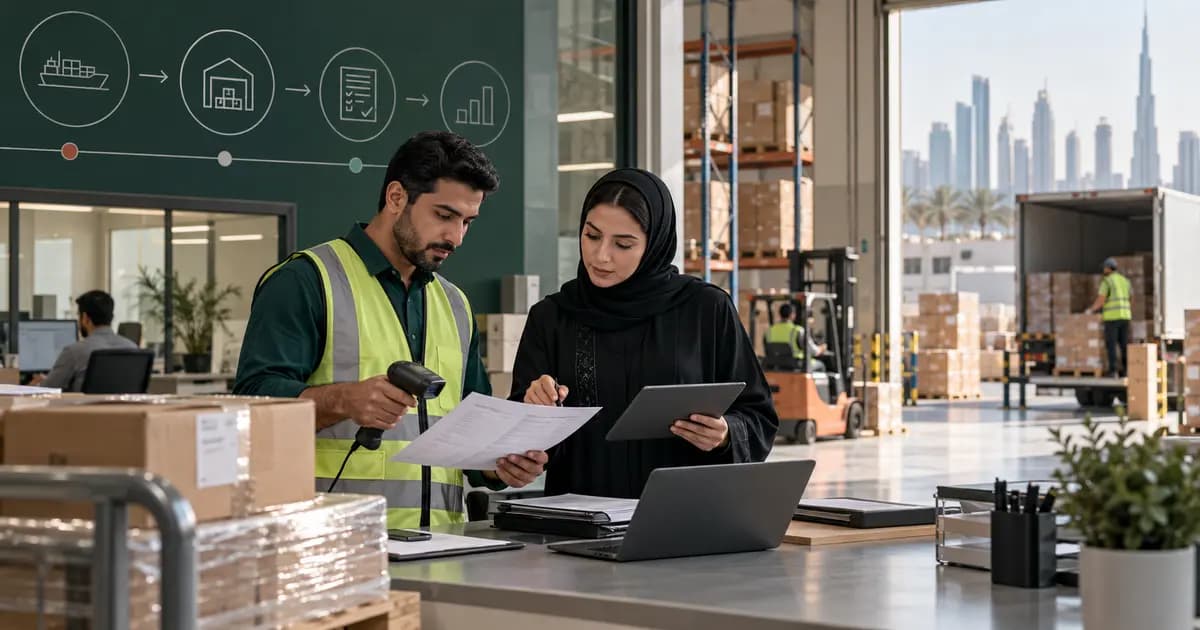
Direct answer
A goods-in-transit reconciliation should connect each open purchase order to supplier dispatch, shipping terms, transport documents, ownership assessment, expected arrival, customs or carrier status, warehouse receipt and inventory posting. At period end, finance should review shipments around cut-off, separate physical location from accounting ownership, investigate receipts without invoices and invoices without receipts, and clear the transit schedule only when supported receipt or other resolution is recorded.
Accounting close map
From information to a controlled decision
- 01Capture
- 02Reconcile
- 03Close
- 04Report
Illustrative evidence trend
Decision supportImported goods can be on a vessel, at a port, with a carrier or in a receiving bay when the month closes. Physical location alone does not determine whether inventory belongs in the accounts. A controlled transit schedule gives procurement, logistics, warehouse and finance one evidence trail for each shipment.
Start with open purchase orders and shipments
Record the legal entity, supplier, purchase order, item, quantity, currency, supplier dispatch date, transport reference, expected arrival and operational owner. Link split shipments and partial receipts to the original order. Remove cancelled lines only with approved evidence.
Capture the contractual ownership evidence
Retain the purchase contract, agreed shipping terms and documents relevant to control of the goods. Do not use an Incoterm label or invoice date as an automatic accounting answer. Finance should document the fact-specific ownership conclusion under the entity's reviewed policy.
Review period-end cut-off
Create a cut-off window around the reporting date and inspect supplier dispatches, bills of lading or airway bills, customs milestones, warehouse receipts and system postings. Focus on items recorded immediately before or after close, manual receipts and high-value shipments.
Reconcile quantity and receipt differences
Compare ordered, shipped, received, rejected, damaged and outstanding quantities. Preserve the warehouse receipt reference and timestamp. Investigate receipts without a linked shipment, duplicate receipts, partial deliveries and quantity changes made after the receiving event.
Separate transit from landed-cost calculation
This control establishes which shipments and quantities remain in transit and how they move into received inventory. Freight, duty and other costs that form part of inventory cost require a separate, supported landed-cost process. Keeping the two schedules linked but distinct prevents missing costs from obscuring receipt exceptions.
Clear items through evidence
Remove an item from the transit schedule only when the warehouse receipt, approved return, cancellation, loss resolution or other supported outcome is recorded. Match later supplier invoices and logistics costs without overwriting the original cut-off evidence.
Goods-in-transit checklist
1. List every open purchase order and shipment. 2. Link dispatch and transport documents. 3. Document the ownership assessment. 4. Review a defined period-end cut-off window. 5. Match ordered, shipped and received quantities. 6. Investigate invoices without receipts and vice versa. 7. Keep receipt control distinct from landed cost. 8. Clear transit items only through supported outcomes.
IAS 2 addresses inventory measurement, including costs incurred to bring inventory to its present location and condition. Contractual terms and transfer of control require fact-specific review. This article provides an operational reconciliation framework, not a universal ownership conclusion.
Editorial practice
Prepared by Valusage Technical Practice. Editorial responsibility rests with Valusage Business Advisors Editorial Practice under the published editorial and corrections policy.
Continue the decision
Services, evidence and next steps
Related control guidance
Continue with another evidence-led management review
 Industry GuidanceDemurrage and Detention Charge Reconciliation Controls for UAE Importers →
 Industry GuidanceFleet Fuel Card and Vehicle Expense Reconciliation Controls for UAE Logistics Businesses →
 Industry GuidanceFranchise Royalty and Sales Report Reconciliation Controls for UAE Networks →
 Accounting and BookkeepingStanding Order and Direct Debit Reconciliation Controls for UAE Businesses →
Professional boundary
This article is general information. It is not a filing opinion, legal advice, audit conclusion, investment recommendation or guarantee of authority acceptance or commercial outcome.
What should a goods-in-transit schedule include?+
Include the entity, supplier, order, shipment, quantity, dispatch evidence, shipping terms, ownership assessment, expected arrival, receipt and open exception.
Does physical arrival determine when imported inventory is recorded?+
Not by itself. The conclusion depends on the contract, transfer of control, supporting facts and the entity’s reviewed accounting policy.
How is goods-in-transit control different from landed-cost accounting?+
Transit control establishes the shipment, ownership and receipt population; landed-cost accounting separately assigns supported freight, duty and related costs to inventory.
Valusage email updates
Receive related Valusage guidance
Original summaries with official sources and practical context. Confirm by email. Unsubscribe at any time.
Relevant next steps
Connect this guidance to a defined requirement
Contextual advisory review
Make every imported shipment traceable through cut-off and warehouse receipt
Describe the entity, decision, deadline and evidence available. The service, enquiry and article path accompany the request. No engagement begins until scope, responsibilities, timing, exclusions and fees are agreed in writing.
Review the related service →Contextual enquiry
Make every imported shipment traceable through cut-off and warehouse receipt
Tell us the outcome, deadline and current position. The selected service context is retained with your request so the right scope can be reviewed.